

Understanding Reverse Mortgage Products
10 Highest Rated Reverse Mortgage Companies for Seniors
Introduction
For many seniors, the journey through reverse mortgages can feel like wandering through a maze, filled with uncertainty and confusion. With so many options available, it’s essential to find companies that offer reliable services and tailored solutions to help you make informed decisions. This article explores ten highly regarded reverse mortgage companies, showcasing their unique offerings and customer satisfaction levels. By understanding their options, seniors can take confident steps toward a more secure financial future.
Angella Conrard, CRMP: Personalized Reverse Mortgage Solutions
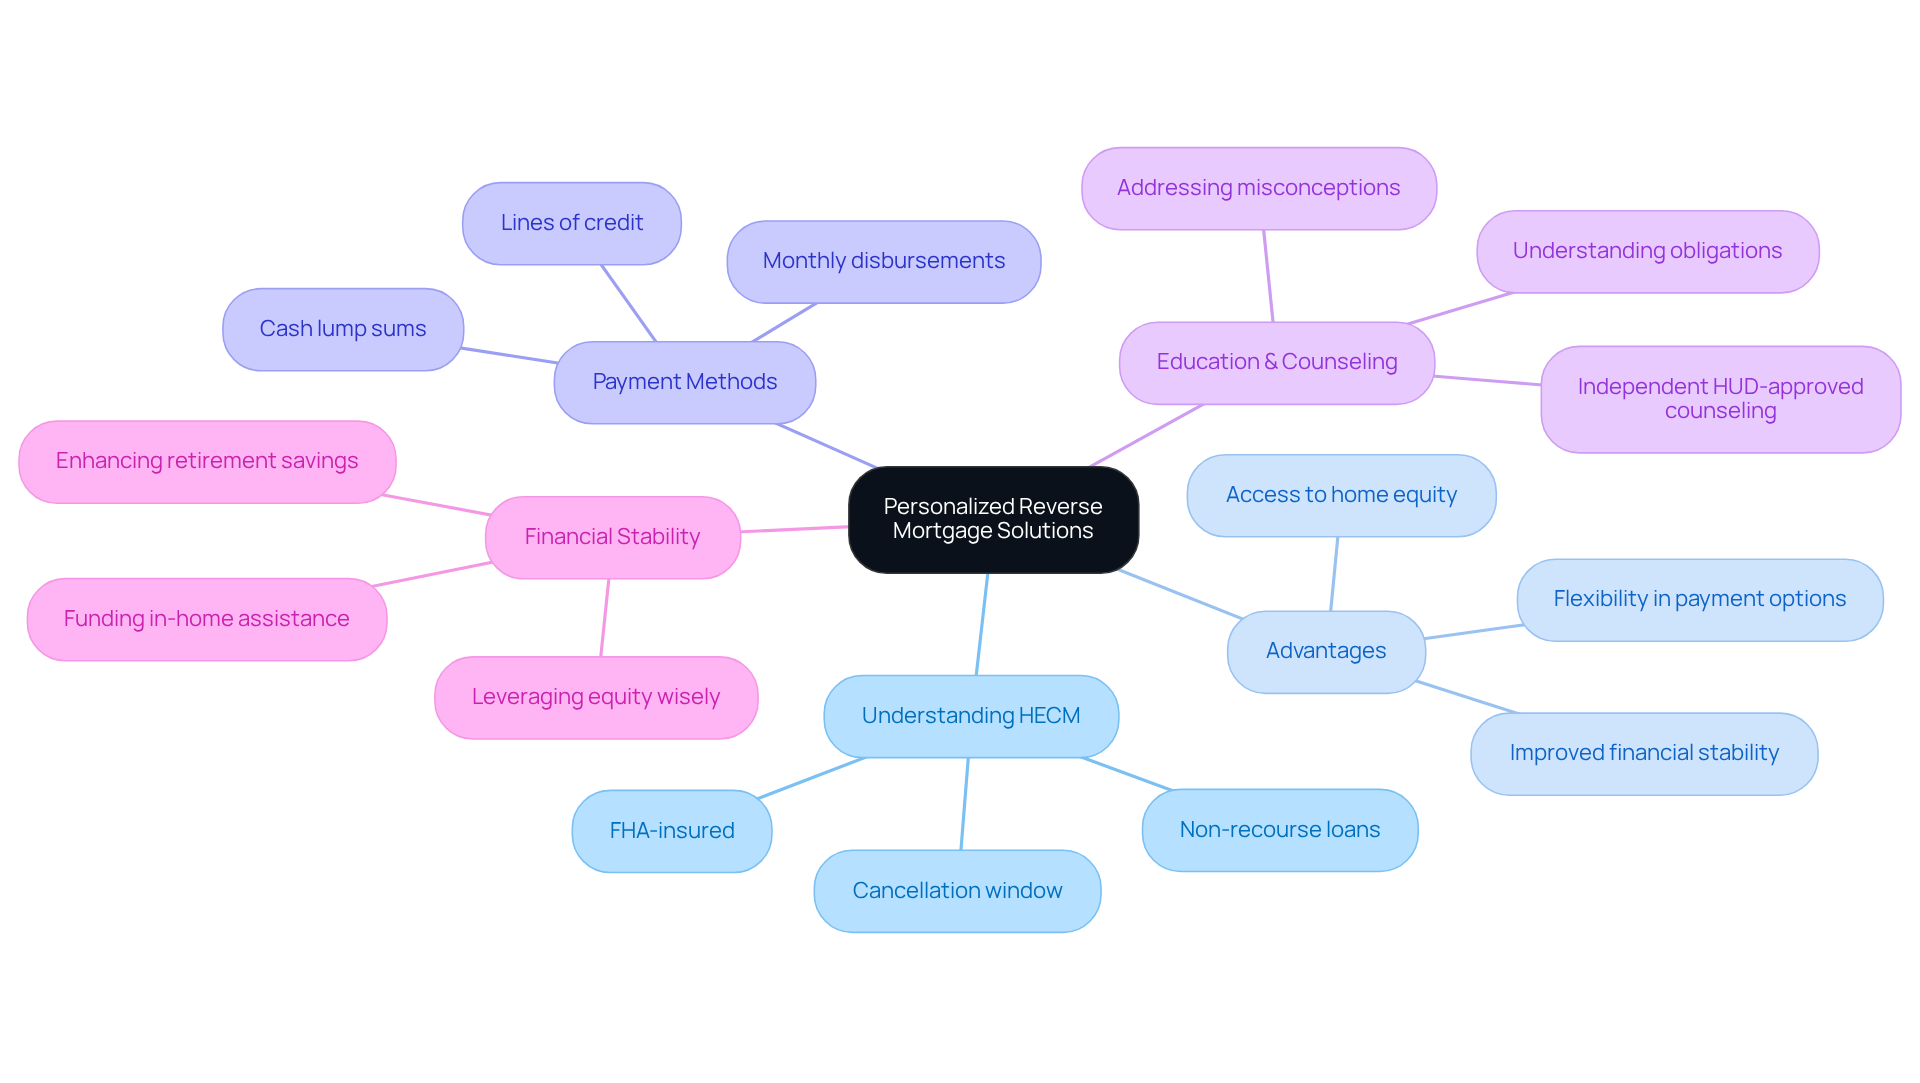
Navigating financial decisions in retirement can feel overwhelming, especially with rising healthcare costs looming on the horizon. As a Certified Reverse Mortgage Professional (CRMP), I take the time to understand your unique financial situation and goals. This way, you can find the options that truly fit your needs. I focus on informing you about the advantages and obligations of a Home Equity Conversion Mortgage (HECM) – an FHA-insured loan that allows qualified property owners, typically aged 62 and above, to access a portion of their property equity through various payment methods, including cash lump sums, lines of credit, or monthly disbursements.
As healthcare costs continue to rise, many seniors worry about how to manage their finances effectively. Leveraging equity wisely can greatly improve financial stability during retirement. Many older homeowners choose a home equity conversion option to adapt their residences for improved mobility, finance in-home assistance, or enhance their retirement savings for travel and leisure. We’re here to help older adults feel empowered in making informed choices that align with their retirement dreams, assisting them in navigating the intricacies of alternative home equity loans and understanding their obligations.
I also recognize that numerous misunderstandings regarding alternative home equity loans persist, often stemming from outdated information. That’s why I prioritize education and independent counseling. An independent HUD-approved counselor is required for FHA-insured and proprietary reverse mortgages to ensure you understand the loan, your responsibilities, and available alternatives. It’s important to note that FHA-insured HECM loans are non-recourse, meaning you will never owe more than your home’s value when the loan becomes due. Additionally, after signing final documents, there is a federally mandated three-day cancellation window, allowing you to reconsider your decision. We want seniors and their families to feel secure and confident in their financial decisions, knowing they have support every step of the way. With the right guidance, you can turn your home equity into a source of comfort and security for your retirement years.
Finance of America: Leading Provider of Reverse Mortgages
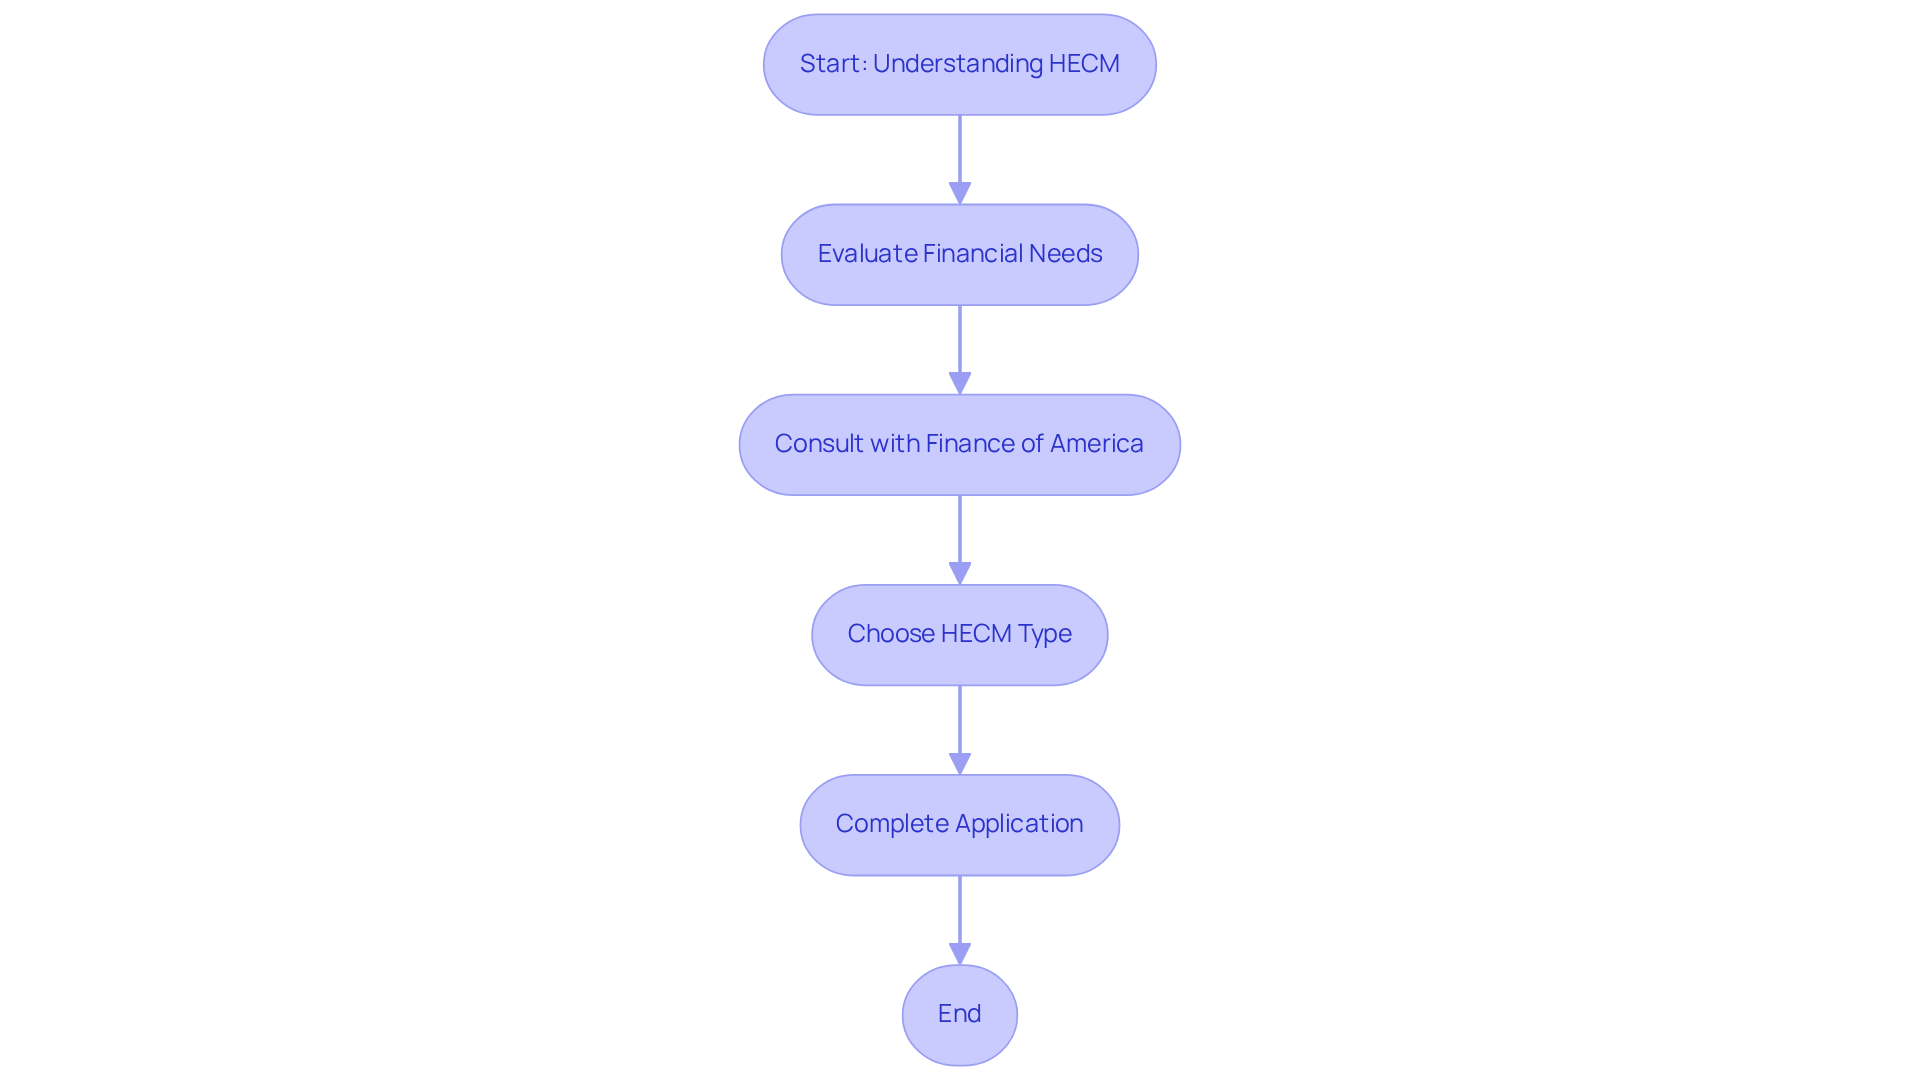
Navigating the world of home equity loans can feel daunting, especially for seniors who want to make the best choices for their future. At Finance of America, we understand that this journey is about more than just numbers; it’s about ensuring your peace of mind. Our clients have rated us 4.4 out of 5, a testament to our dedication to providing reliable service and a range of home equity options tailored to meet their needs, including FHA-insured Home Equity Conversion Mortgages (HECMs).
Our caring team is here to guide older homeowners through the financing process, helping them understand their choices so they can make informed decisions about their property equity. A Home Equity Conversion Mortgage (HECM) allows qualified property owners, typically aged 62 and older, to access a portion of their equity through various options like cash lump sums or monthly payments. We know that some proprietary programs even start at age 55, making it easier for more seniors to benefit.
In 2026, we proudly announced a funded volume of $730 million in alternative home equity loans, reflecting a 21% rise from the previous year. This growth shows our commitment to providing effective retirement solutions that emphasize alternative financing and equity products. We’ve also expanded our HomeSafe Second offering, allowing property owners aged 55 and older to tap into their equity without adding a new monthly payment, helping them maintain their current low-rate primary loan.
Customer experience is our priority. We’re here to provide educational resources and support throughout the application process. Our approach not only helps older adults navigate the complexities of alternative financing but also empowers them to leverage their property equity effectively during retirement. Many retirees use funds from a reverse mortgage to adapt their homes for better mobility, cover in-home assistance, or enhance their retirement savings for travel and leisure.
It’s important to understand that the loan becomes due when a maturity event occurs, such as when the last borrower permanently vacates the residence, sells the property, or passes away. FHA-insured HECM loans are non-recourse, meaning that heirs will never owe more than the property’s value. We encourage family members to be involved in the process, ensuring that options for heirs – like selling the home, refinancing to keep it, or purchasing it – are clearly explained well before decisions need to be made. By understanding their options, seniors can take control of their financial future, ensuring they live comfortably and confidently in their golden years.
Longbridge Financial: Competitive Rates and Innovative Products
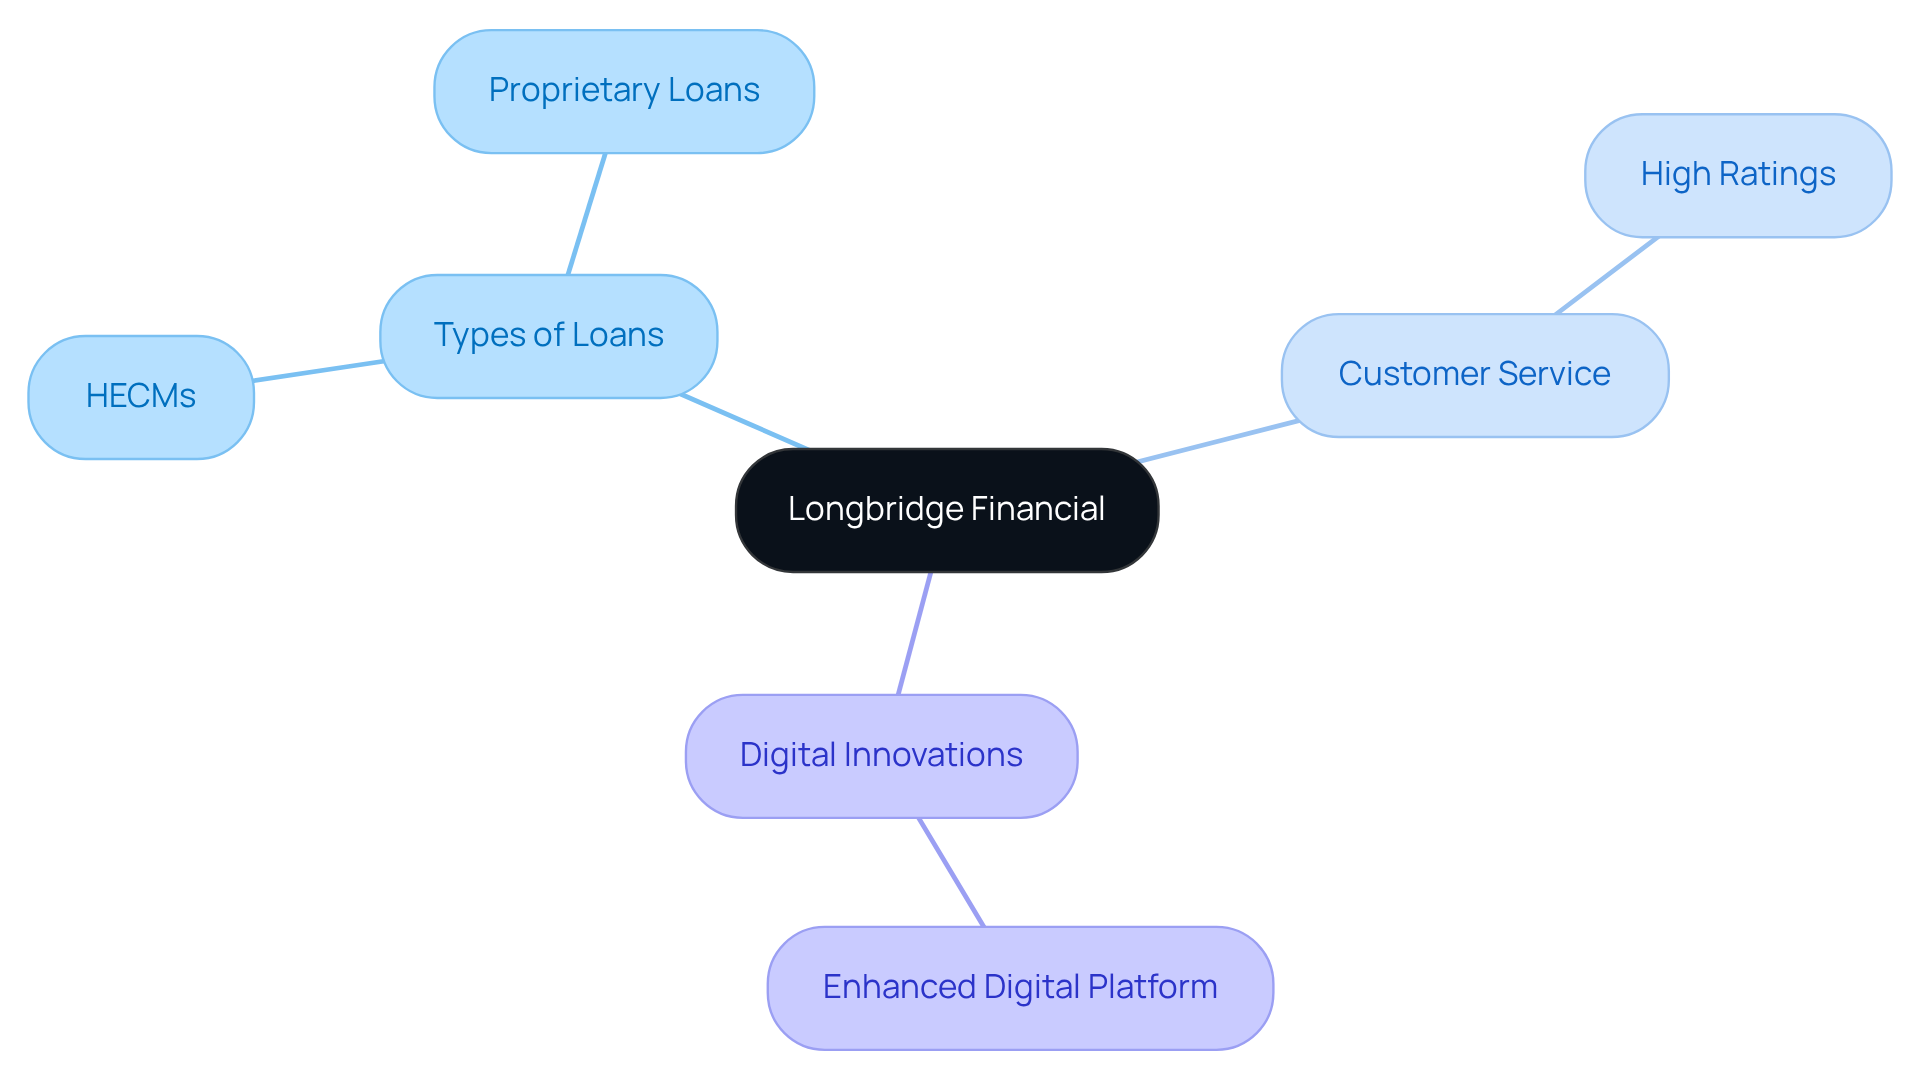
Navigating financial options can be overwhelming for seniors, especially when it comes to accessing the equity in their homes. Longbridge Financial is recognized as one of the highest rated reverse mortgage companies, offering a range of solutions designed with your needs in mind. They provide various options, including traditional Home Equity Conversion Mortgages (HECMs) and proprietary loans, ensuring that you have choices that fit your unique situation. We understand how important it is for you to feel supported and valued during this process, and Longbridge’s commitment to customer service is reflected in their recognition as one of the highest rated reverse mortgage companies.
In 2026, many seniors found that the average adjustable-rate loan for HECMs was reported at 5.81%, a figure that can feel daunting. However, with Longbridge’s user-friendly online tools and resources, you can navigate these numbers with confidence. They aim to enhance your borrowing experience, ensuring you feel supported every step of the way.
Additionally, their recent initiatives, like the launch of an enhanced digital platform, are designed to streamline applications and improve accessibility for you. As more financial institutions recognize the importance of retirement-focused lending solutions, you can feel reassured that options are expanding. With Longbridge by your side, you can confidently explore your options and secure a brighter financial future.
Guild Mortgage: Exceptional Customer Satisfaction and Resources
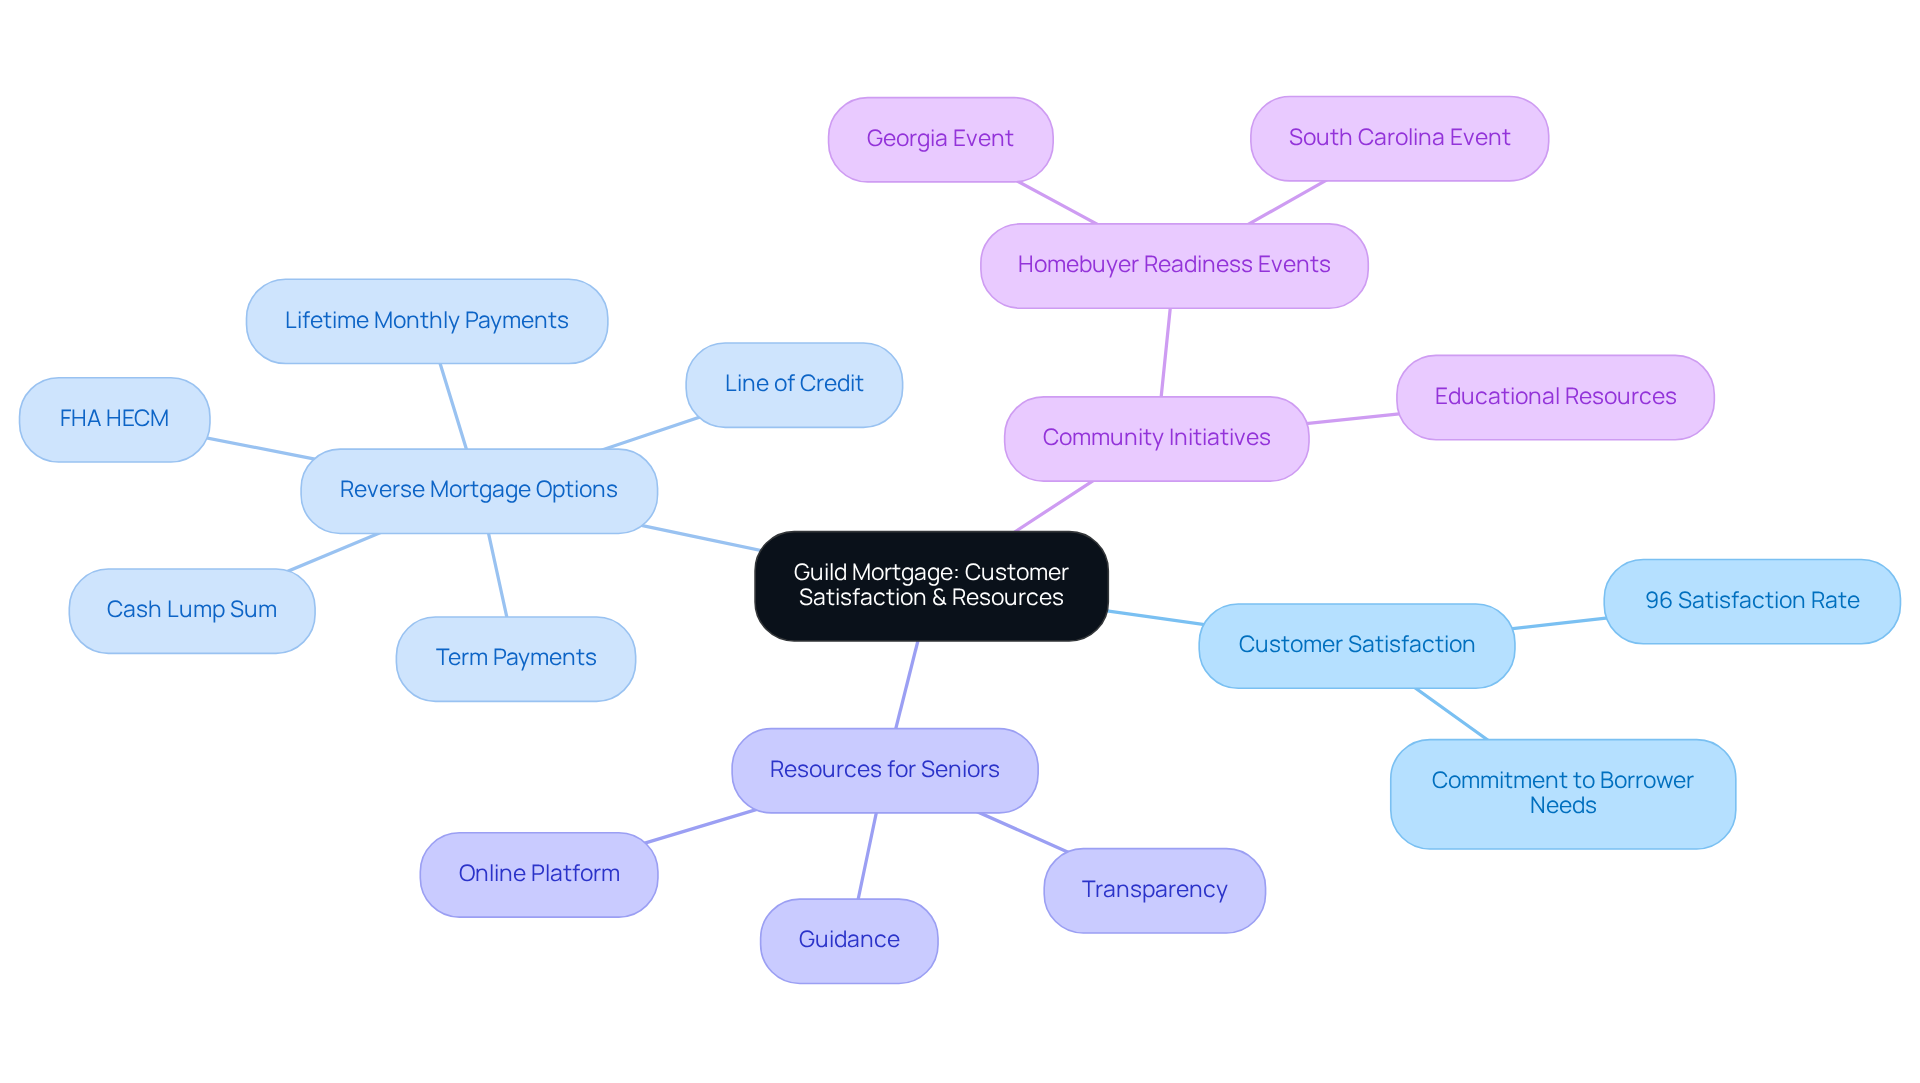
Many seniors worry about their financial security, but Guild Mortgage stands out as a beacon of support and satisfaction for borrowers. In 2026, Guild Mortgage earned a remarkable 96% satisfaction rate, a testament to their genuine commitment to understanding and meeting the needs of borrowers like you. They offer a variety of reverse mortgage options, including FHA-insured Home Equity Conversion Mortgages (HECMs), which allow retirees aged 62 and above to tap into their home equity. With choices like a cash lump sum, line of credit, term payments, or lifetime monthly payments, this flexibility means that seniors can access funds for important needs, whether it’s making their homes more accessible, covering in-home care, or boosting their retirement savings for peace of mind.
Navigating the borrowing process can feel overwhelming for many seniors, leaving them uncertain about their options. But with Guild Mortgage’s resources and guidance, seniors can feel empowered to make informed decisions about their financial futures. Their easy-to-use online platform provides straightforward information and helps borrowers manage their loans, enhancing the overall experience. Plus, Guild’s commitment to transparency ensures that clients feel informed and confident in their decisions, including understanding the importance of maintaining their property and keeping taxes and insurance current.
Case studies highlight Guild Mortgage’s proactive approach to customer service. For instance, their recent Homebuyer Readiness Events in Georgia and South Carolina successfully educated potential homeowners about the homebuying process, fostering a supportive community environment. Such initiatives showcase Guild’s commitment to empowering older adults and their families.
Ultimately, Guild Mortgage not only offers financing solutions but also a compassionate partnership that helps seniors navigate their financial journeys with confidence.
Fairway Independent Mortgage: Fast and Efficient Closing
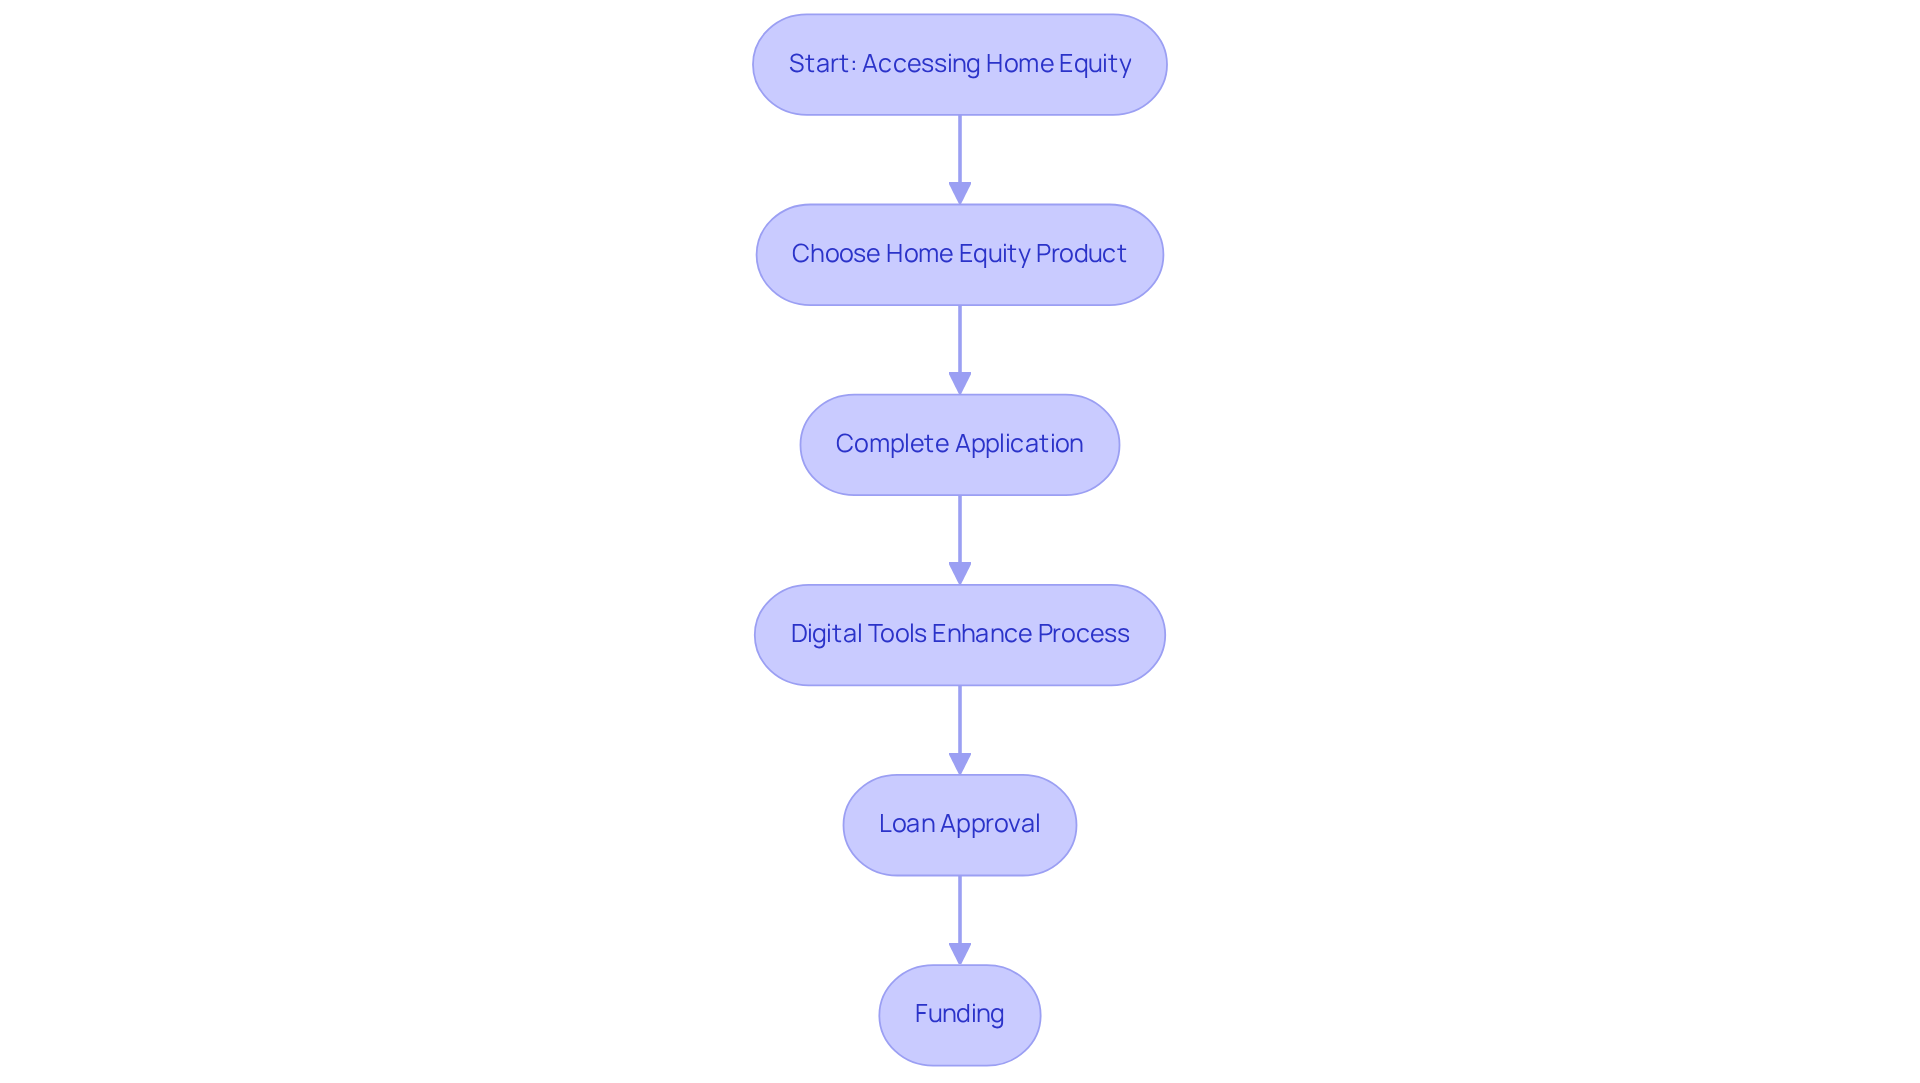
Many seniors feel overwhelmed when trying to access their home equity, often unsure of where to start. Fairway Independent Mortgage offers a fast and efficient closing process that can help ease those worries. They provide a range of alternative home equity products, including FHA-insured Home Equity Conversion Mortgages (HECMs), and highlight a simplified application process. At Fairway, we understand that staying informed is crucial for our clients, and we’re here to guide you every step of the way, making the journey from application to funding as smooth as possible.
In 2026, the typical closing duration for alternative home financing is expected to be considerably shortened, with numerous loans concluding within 30 to 60 days from application to funding. This commitment to service means that older homeowners can trust Fairway to help them explore their financial possibilities with confidence and care. Expert opinions highlight their dedication to customer service and operational excellence, reinforcing Fairway’s strong standing in the alternative financing sector.
A Home Equity Conversion Mortgage (HECM), often referred to as a cash-out mortgage, is an FHA-insured loan that enables qualified property owners to access a portion of their equity through a cash lump sum, line of credit, monthly payments, or a combination of these options. HECM borrowers are generally age 62+, with provisions for eligible non-borrowing spouses under 62. With a Washington reverse mortgage, older homeowners can select how they receive their payout, whether through a line of credit, cash out, or monthly payments. This adaptability enables older adults to use the funds for different requirements, such as modifications to their residences for improved mobility or in-home assistance as they age in place.
Additionally, Fairway’s innovative approach includes integrating digital tools to enhance the application process, which has been shown to improve loan approval efficiency by 33%. This dedication to utilizing technology not only accelerates the closing process but also improves the overall customer experience, facilitating access to the funds they require. Significantly, FHA-insured HECM loans are non-recourse, indicating that borrowers never owe more than the home’s worth when the loan is due, offering reassurance for older homeowners and their families. With Fairway, you’re not just getting a loan; you’re gaining a partner in your financial journey, ensuring you’re never alone in this process.
Mutual of Omaha: Strong In-Person Experience for Seniors
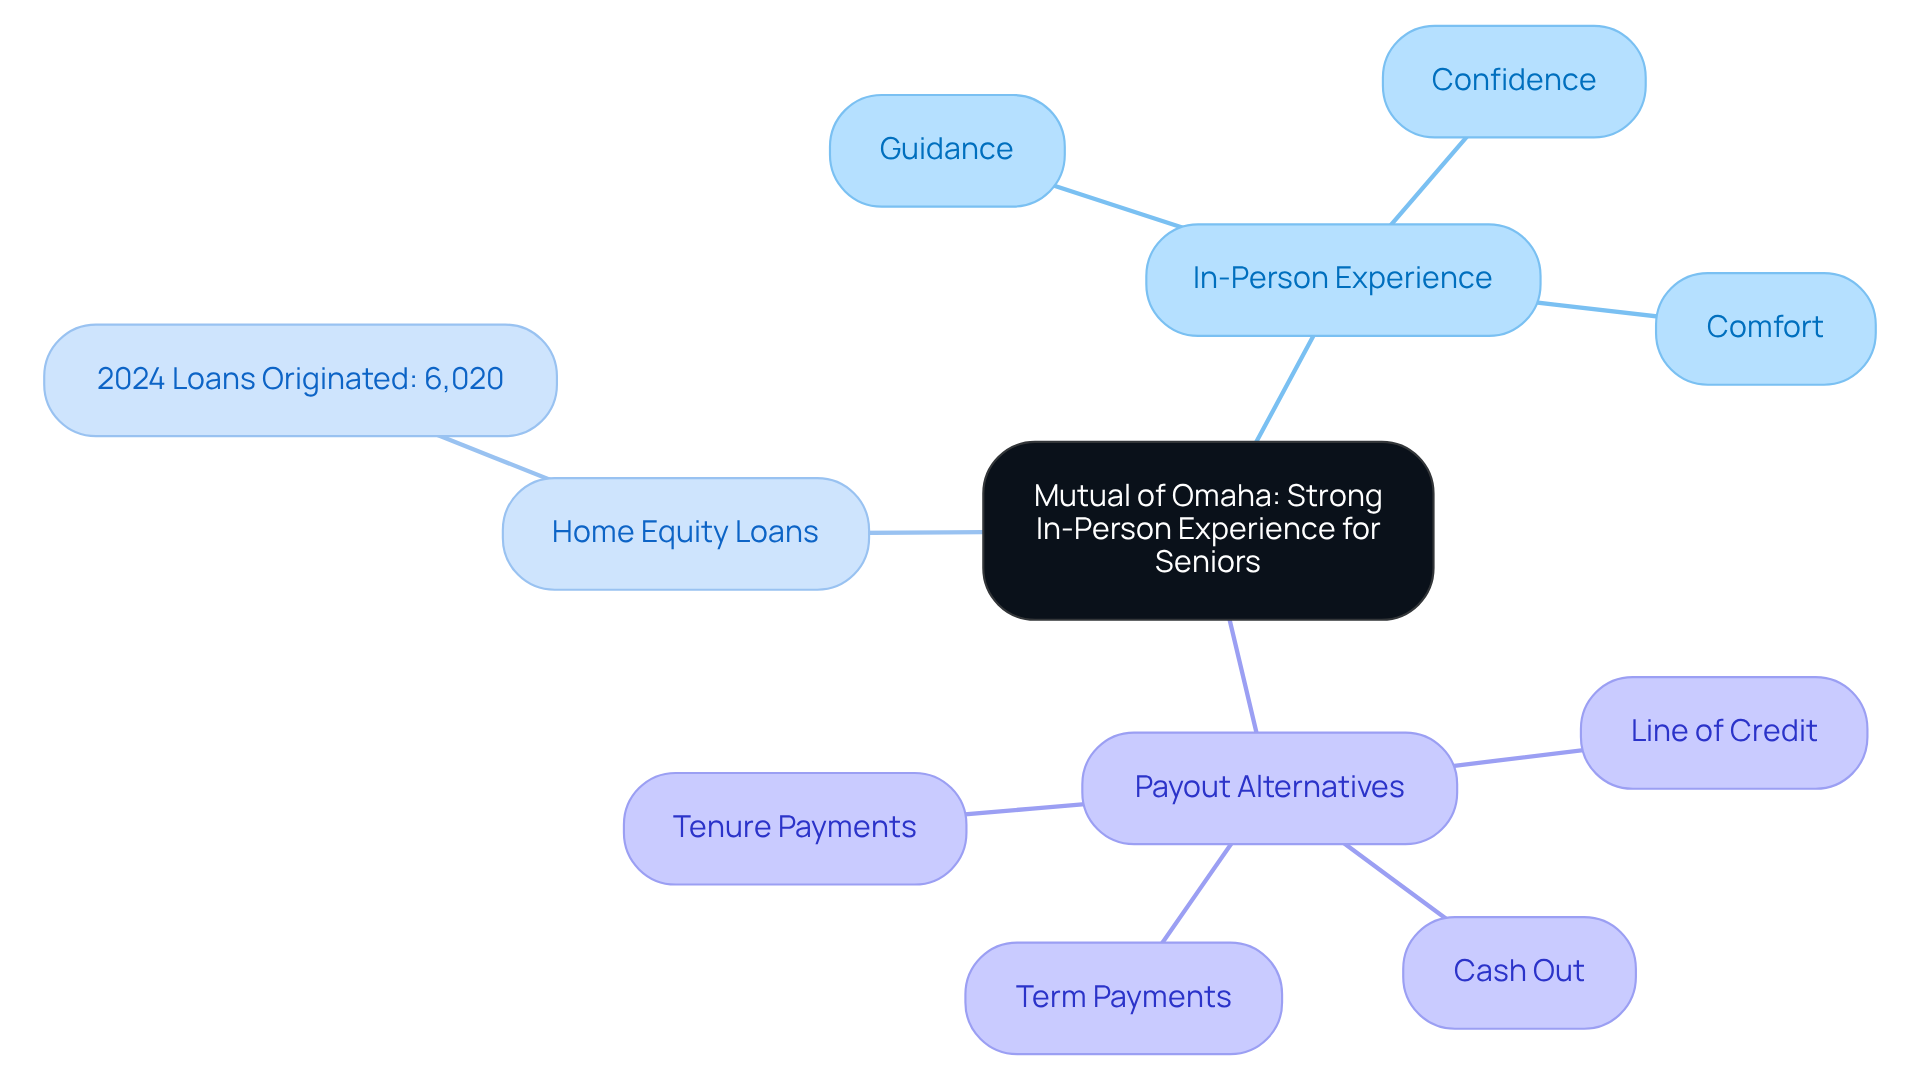
For many seniors, navigating financial decisions can feel overwhelming, especially when it comes to home equity loans. Mutual of Omaha is recognized for its strong in-person experience, making it a preferred choice for those who appreciate face-to-face interactions. Their dedicated team is here to guide you through the financing process, ensuring you feel comfortable and confident in your choices.
In 2024, Mutual of Omaha originated 6,020 home equity loans, showing their strong focus on helping seniors access the funds they need. This commitment to personalized service meets the unique needs of older homeowners, reinforcing their reputation for reliability and support. Furthermore, many older adults prefer direct interactions when making financial choices, emphasizing the significance of face-to-face service.
By fostering a supportive environment, Mutual of Omaha positions itself as a trusted partner in retirement financing. Comprehending the different payout alternatives accessible through a Washington mortgage-such as a line of credit, cash out, term payments, or tenure payments-can empower older homeowners to effectively utilize their property equity, whether for modifications, in-home assistance, or enhancing their retirement lifestyle.
When you understand your options, you can take control of your financial future and enjoy the retirement you deserve.
CrossCountry Mortgage: Reliable and High-Performing Lender
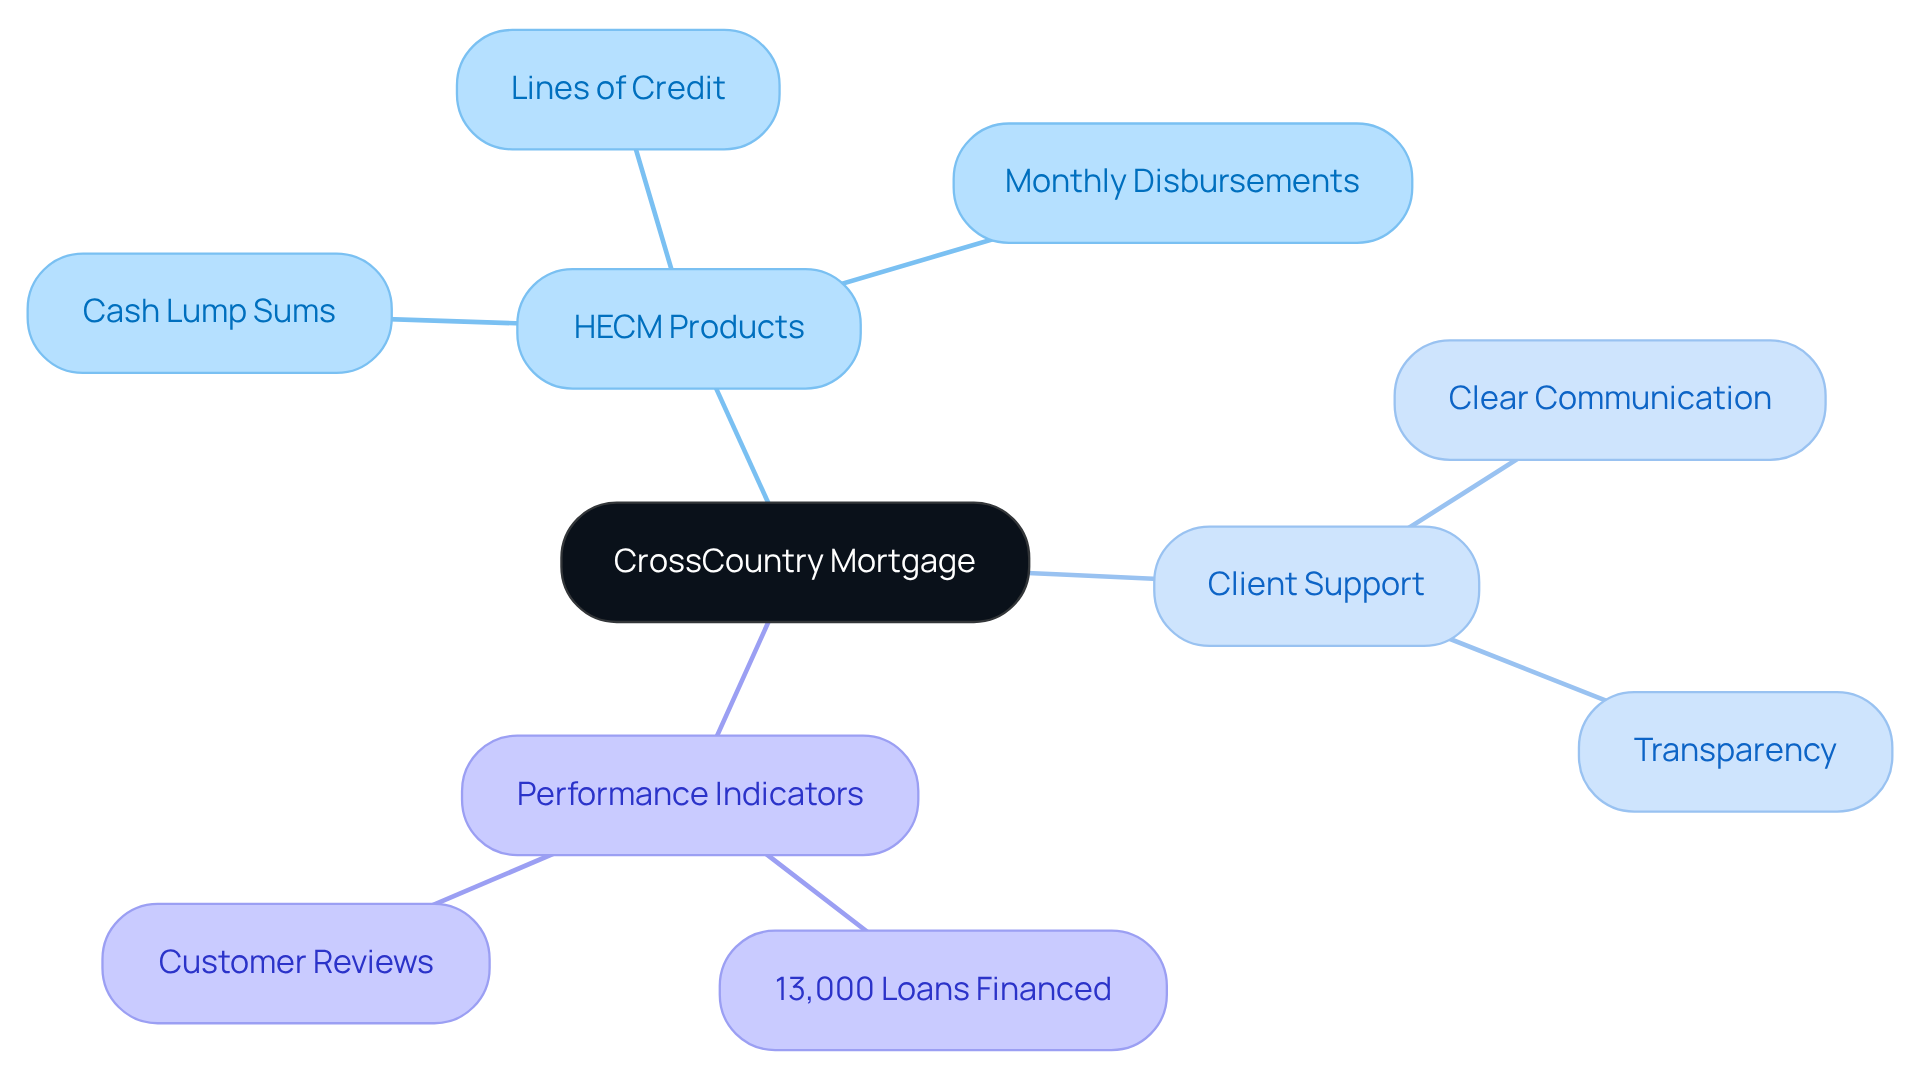
Many seniors worry about how to access their home equity without adding financial stress. CrossCountry Mortgage is a trusted name in alternative financing, offering support when it’s needed most. They provide a variety of products, including FHA-insured Home Equity Conversion Mortgages (HECMs), which allow older homeowners to tap into their property equity through options like cash lump sums, lines of credit, or monthly disbursements.
We understand that navigating the loan process can be daunting, but CrossCountry’s clear communication and transparency help ease those worries, allowing you to feel secure in your decisions. With a strong history of financing over 13,000 alternative home equity loans in 2024, their performance indicators and positive customer reviews establish them as a reliable choice for retirees looking to utilize their home equity.
Their commitment to client satisfaction shines through, as they’ve been recognized as the country’s largest alternative home equity lender by volume. Many clients have shared how CrossCountry has helped them manage the complexities of alternative home financing, enhancing their financial flexibility during retirement. With CrossCountry Mortgage, you’re not just getting a loan; you’re gaining a partner who understands your needs and is here to support you every step of the way.
PHH Mortgage: Transparent Fees and Costs
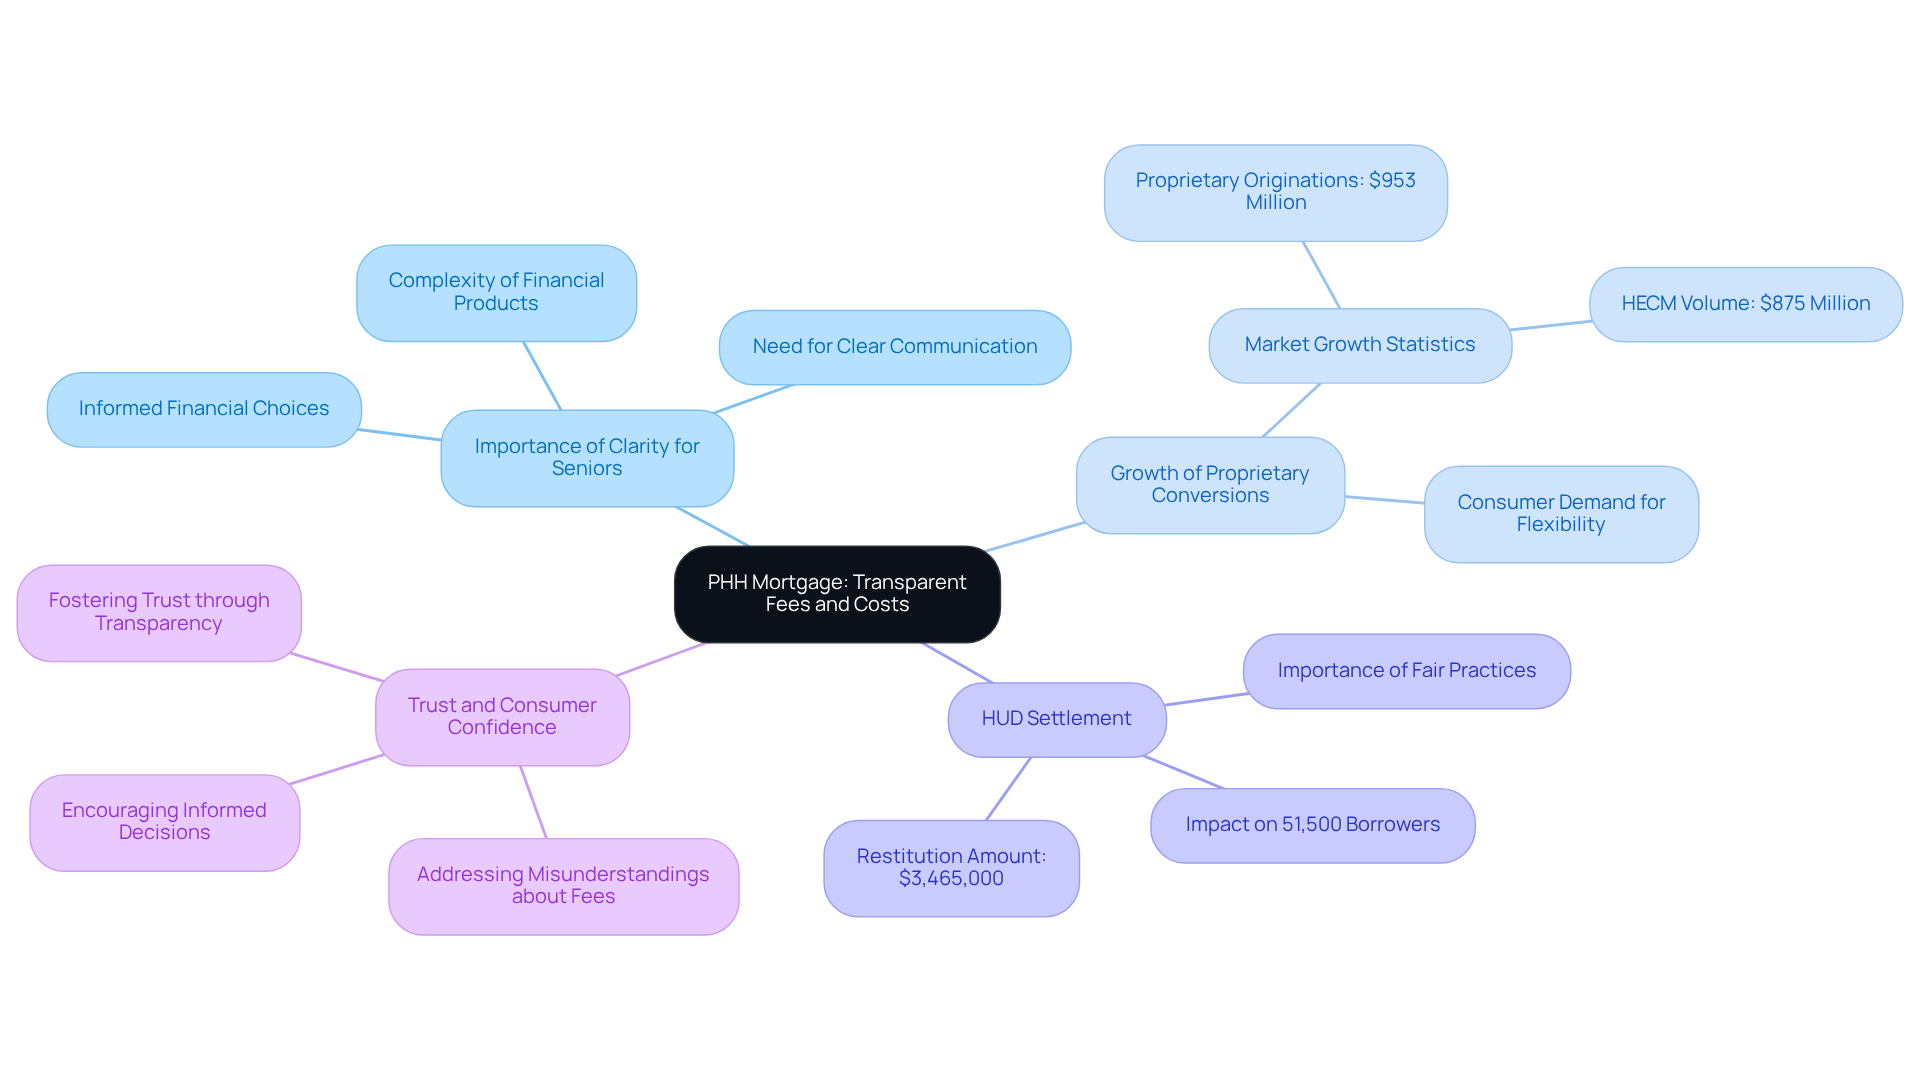
Navigating financial choices can be daunting, especially for seniors who deserve clarity and support in their decisions. PHH Mortgage stands out because we truly care about providing clear fees and costs, helping older homeowners make informed financial choices. We offer comprehensive information about the costs associated with our products, including FHA-insured Home Equity Conversion Mortgages (HECMs). This clarity is crucial, especially since many borrowers feel overwhelmed by the complexity of financial products, fearing they might make the wrong choice. It’s easy to misunderstand fee structures, particularly when many assume that fees for alternative financing are similar to those in the HECM program.
In the initial quarter of 2026, proprietary home equity conversions reached around $953 million, surpassing HECM volume of approximately $875 million. This growth shows that more homeowners with valuable properties are looking for flexible financial options. As the proprietary market expands, the need for clear fee structures becomes even more critical to maintain consumer trust. When borrowers understand the costs involved, they can make confident decisions that secure their financial future.
Moreover, a recent settlement involving PHH Mortgage highlighted the importance of fair practices in the industry. The U.S. Department of Housing and Urban Development (HUD) reached a historic settlement with PHH regarding allegations of unlawful fees charged to borrowers, resulting in approximately $3,465,000 in restitution for about 51,500 borrowers. This agreement reinforces the notion that borrowers should feel informed and valued in their financial choices, emphasizing transparency and accountability in loan servicing.
By emphasizing clear communication regarding fees and expenses, PHH Mortgage fosters trust with borrowers, enabling them to navigate the intricacies of alternative financing options with assurance. If you’re considering an alternative financial arrangement, please reach out to me, Angella Conrard, CRMP. I’m here to provide personalized support tailored to your unique situation.
New American Funding: Supporting Underserved Households
Many older adults are feeling the weight of financial uncertainty, struggling to make ends meet as costs rise. New American Funding understands these challenges and is committed to assisting underserved households, making it a valuable choice for older adults from various backgrounds. They truly care about their clients, making sure everyone feels valued and understood.
Despite the challenges in the reverse mortgage market, many older adults are feeling the weight of financial uncertainty, struggling to make ends meet as costs rise. New American Funding provides a range of alternative equity products, including FHA-insured Home Equity Conversion Loans (HECLs), emphasizing fair access to equity solutions. Their tailored solutions help ease these worries, allowing seniors to feel more secure in their financial futures.
Their approach not only aids in accessing home equity but also fosters a sense of security for retirees looking to enhance their financial flexibility. With New American Funding, you’re not just accessing equity; you’re finding a path to a more secure and fulfilling retirement.
C2 Financial Corporation: Customized Solutions for Seniors
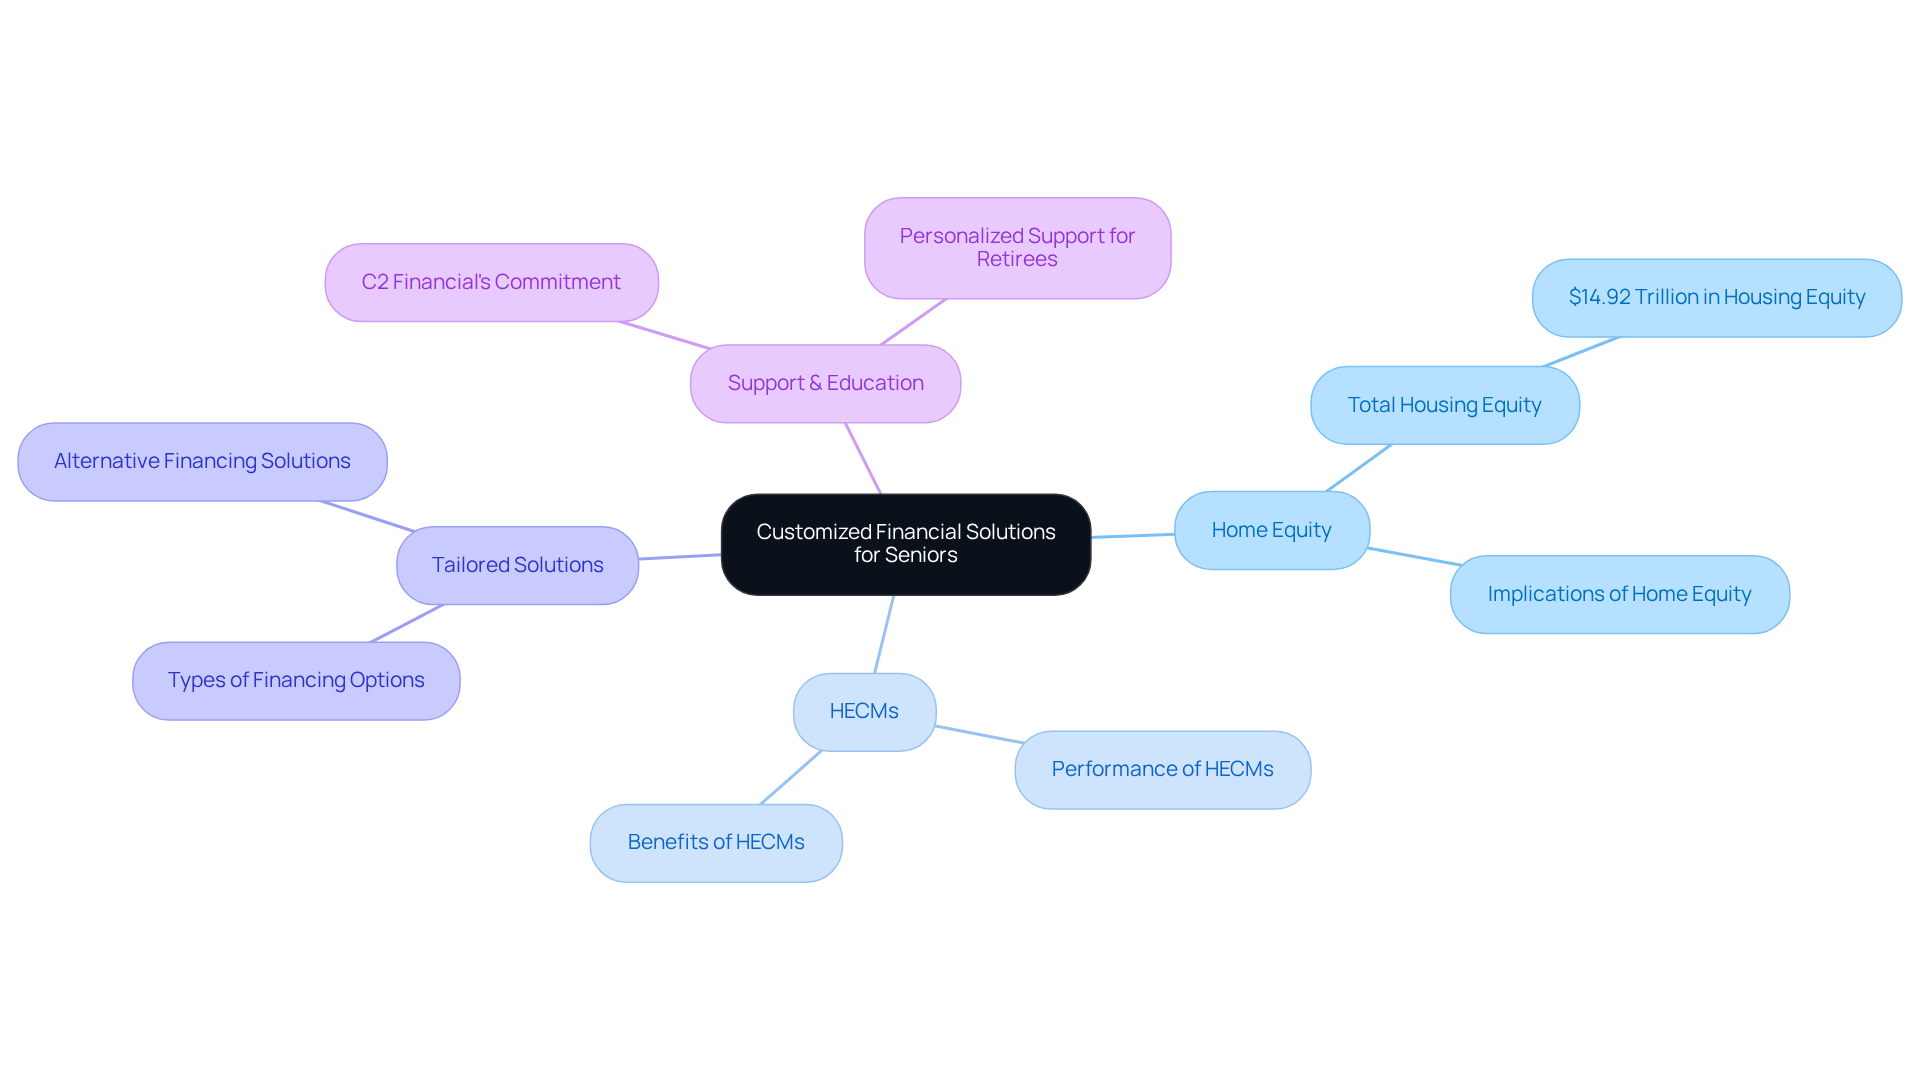
We understand that navigating financial options can feel overwhelming for older homeowners, especially when it comes to making the right choices for their future. At C2 Financial Corporation, we’re here to help you explore tailored solutions that fit your unique financial situation and goals. Our experienced professionals work closely with you, ensuring you receive the most appropriate options available.
Did you know that many homeowners aged 62 and above hold nearly $14.92 trillion in housing equity? This significant value can open doors to alternative financing solutions that may ease financial burdens. However, many older property owners with low-rate primary loans might feel hesitant to refinance traditionally, which is why tailored alternative financing options are increasingly important.
By leveraging advanced analytical tools, we can better understand how home equity conversion mortgages (HECMs) perform, ensuring that you receive the best possible guidance tailored to your unique situation. This approach aligns with our commitment to comprehending the financial dynamics of the alternative equity loan market, ultimately benefiting you as a borrower.
At C2 Financial, we’re dedicated to providing personalized support and education, ensuring you feel confident and informed as you navigate your financial future. With the right support and understanding, you can confidently explore the financial options that best suit your needs and dreams.
Conclusion
Many seniors feel overwhelmed by the choices and information surrounding reverse mortgages, but understanding these options is key to making informed financial decisions. This article has highlighted several reputable companies that provide tailored reverse mortgage solutions, emphasizing the importance of personalized service and education in this process. Every company we talked about brings something special to the table, helping older homeowners find the right fit for their unique needs and dreams.
Key insights include the significance of FHA-insured Home Equity Conversion Mortgages (HECMs), which allow seniors to access their home equity while ensuring that they never owe more than the home’s value. We also underscored the necessity of independent counseling and the involvement of family members in the decision-making process, providing a comprehensive view of the responsibilities and options available to heirs. By exploring the offerings from companies like Finance of America, Longbridge Financial, and others, seniors can feel empowered to leverage their home equity effectively.
Ultimately, it’s about making choices that truly enhance your quality of life. Seniors are encouraged to seek personalized guidance, whether through a consultation with a Certified Reverse Mortgage Professional like Angella Conrard or by exploring the resources available on reputable company websites. Taking the time to understand these options can lead to a more secure and fulfilling retirement, allowing older adults to enjoy their golden years with confidence and peace of mind.
Frequently Asked Questions
What is a Home Equity Conversion Mortgage (HECM)?
A Home Equity Conversion Mortgage (HECM) is an FHA-insured loan that allows eligible homeowners, typically aged 62 and above, to access a portion of their home equity through various payment methods, including cash lump sums, lines of credit, or monthly payments.
Who is eligible for a HECM?
HECM borrowers are generally age 62 and older, with provisions for eligible non-borrowing spouses under 62. Some proprietary programs may start at age 55.
What are the benefits of a HECM for seniors?
A HECM can help seniors improve financial stability during retirement by allowing them to leverage their home equity for various needs, such as adapting their homes for better mobility, financing in-home assistance, or enhancing retirement savings for travel and leisure.
What are the obligations associated with a HECM?
Borrowers must continue to pay property taxes, homeowners insurance, and maintain the property as their primary residence. FHA-insured HECM loans are non-recourse, meaning borrowers will never owe more than the home’s value when the loan becomes due.
What happens when the loan becomes due?
The loan becomes due when the last borrower permanently leaves the home, sells the property, or passes away. Heirs have options to sell the home, refinance to keep it, or purchase it, and they will never owe more than the property’s value.
Is independent counseling required for HECMs?
Yes, an independent HUD-approved counselor is required for FHA-insured and proprietary reverse mortgages to ensure borrowers understand the loan, their responsibilities, and available alternatives.
What is the cancellation window after signing HECM documents?
After signing the final documents, there is a federally mandated three-day cancellation window, allowing borrowers to reconsider their decision.
How can family members be involved in the HECM process?
Family members are encouraged to participate in the process to ensure everyone understands the options available and feels comfortable with the decisions being made.
How long does the HECM application process take?
The application process typically takes about 30 to 60 days from application to funding, with various steps including consultation, financial assessment, and underwriting.
What resources are available for seniors considering a HECM?
Seniors can access educational resources and support throughout the application process to help them navigate the complexities of alternative financing and leverage their property equity effectively during retirement.
Have questions about this?
Talk to a Certified Reverse Mortgage Professional — directly.
When you call, you reach me — not a call center. Free 30-minute consult by phone, video, or in person. No SSN, no credit pull, no obligation.
Schedule a consult