

Reverse Mortgages 101
7 Benefits of Working with HUD-Approved Reverse Mortgage Counselors
Introduction
Many older homeowners feel overwhelmed and anxious when faced with the complexities of reverse mortgages. It’s important to grasp how these financial products work, especially when your future is at stake. Working with HUD-approved reverse mortgage counselors can provide the support you need during this challenging time. This article explores how these professionals can empower you to make informed decisions while avoiding common pitfalls. Let’s explore how partnering with a HUD-approved counselor can make this journey smoother and more reassuring for you.
Angella Conrard, CRMP: Personalized Guidance from a Certified Reverse Mortgage Professional
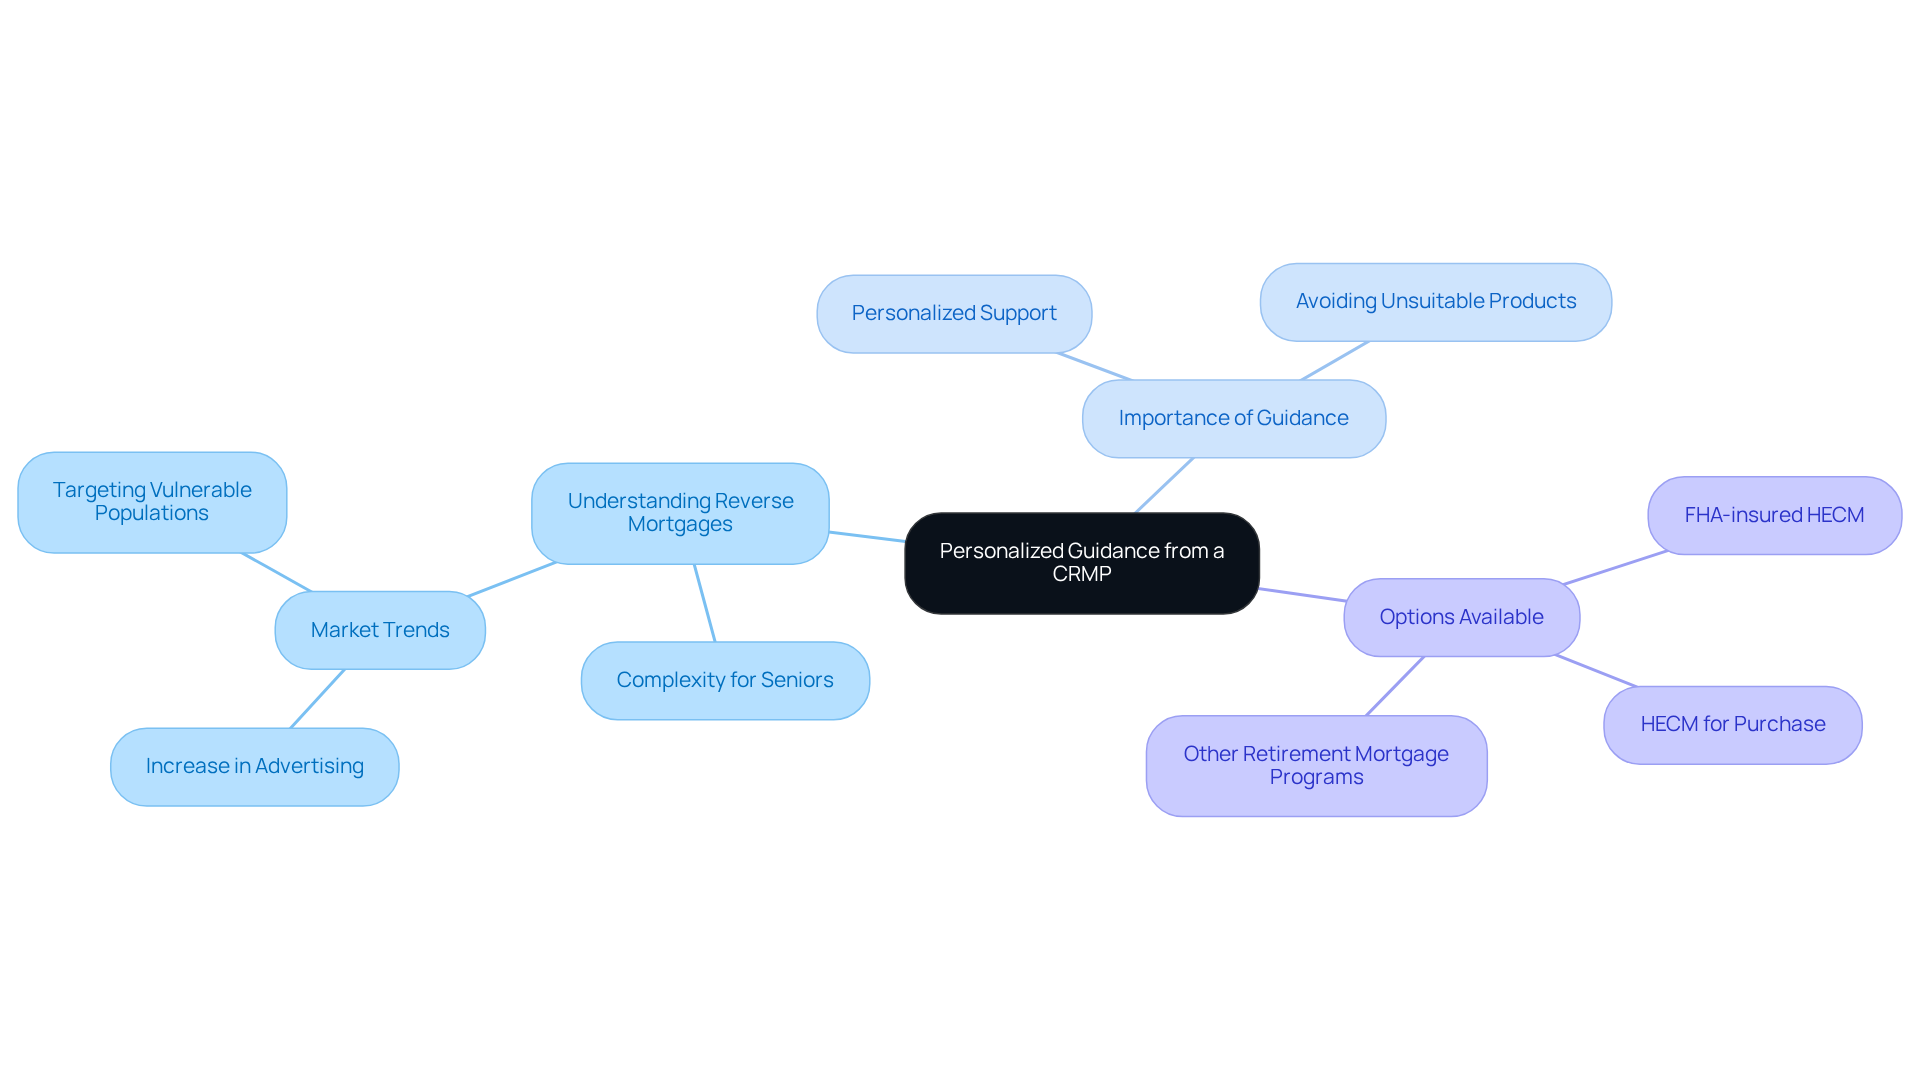
Navigating the world of reverse mortgages can feel daunting for many seniors, leaving them anxious about their financial futures. As a Certified Reverse Mortgage Professional (CRMP), I’m here to help guide you through this process. I understand that each person’s financial situation is unique, and I’m committed to providing you with the clear, unbiased information you need to make informed decisions about your retirement funding.
Many seniors feel overwhelmed and anxious when faced with complex financial decisions, especially regarding their homes. The need for clear and unbiased information is underscored by the fact that the older adult population is projected to grow significantly, from approximately 49.2 million in 2016 to about 94.7 million by 2060, marking a 92 percent increase. As the number of older adults grows, many are left feeling uncertain about their financial options. That’s why having a knowledgeable professional by your side is so crucial.
Additionally, the Consumer Financial Protection Bureau (CFPB) has observed a four-fold rise in reverse home equity loan advertising since 2019, mainly aimed at older property owners with significant equity and lower incomes. This trend emphasizes the necessity for consumers to seek guidance from HUD-approved reverse mortgage counselors who can assist them in navigating the market and avoiding potentially unsuitable products.
When you work with a CRMP like me, you can expect to gain a clear understanding of your options, including:
- FHA-insured Home Equity Conversion Mortgages (HECM)
- HECM for Purchase
- Other retirement mortgage programs
I strive to ensure that my clients feel confident in their decisions, knowing they have received personalized and unbiased advice tailored to their specific needs. With the right support, you can turn uncertainty into confidence, ensuring your retirement years are as fulfilling as they should be.
Assurance of Quality: The Importance of HUD Approval in Counseling
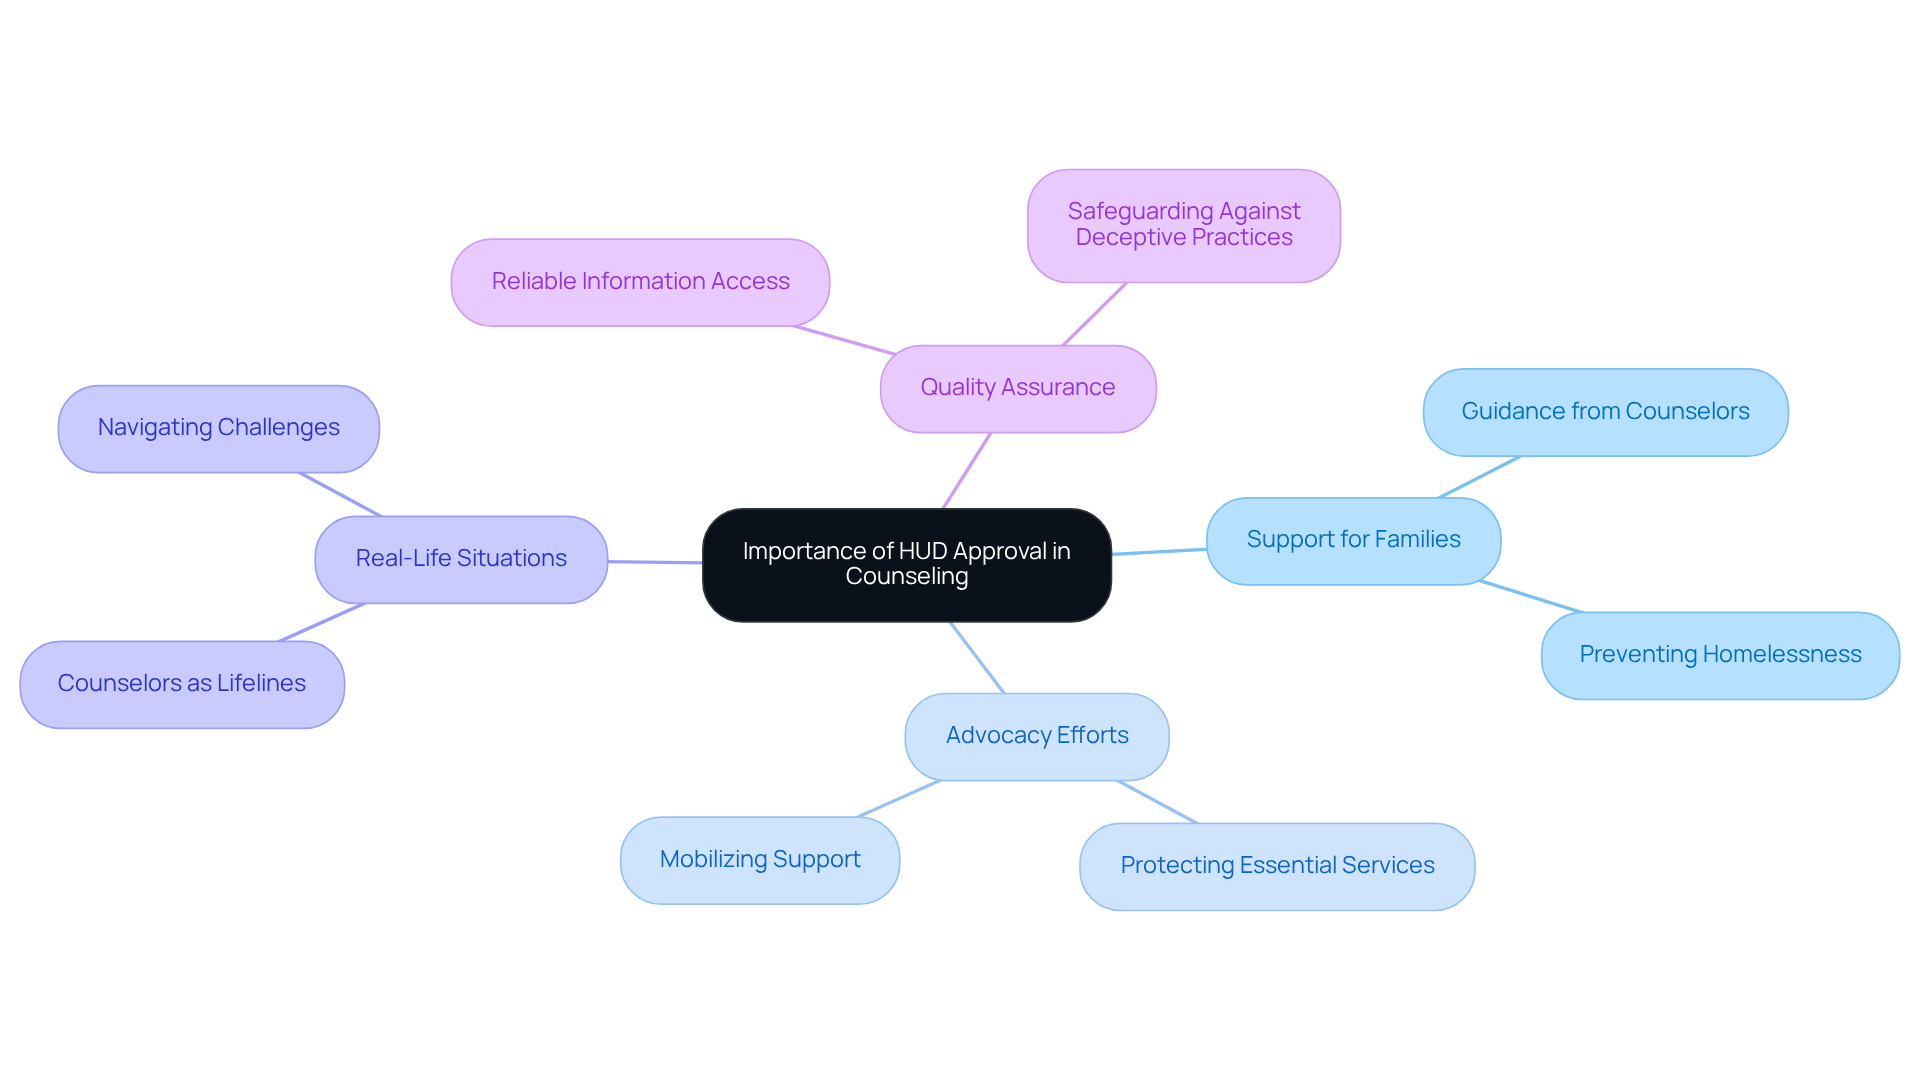
Imagine facing the uncertainty of homeownership without the guidance of a trusted counselor – this is the reality for many families today. When you work with HUD-approved reverse mortgage counselors, you’re not just getting information; you’re gaining a trusted partner who understands your unique situation. Every year, nearly a million households find hope and support through HUD-approved reverse mortgage counselors, which helps them navigate their housing challenges with confidence.
However, recent changes to HUD’s funding have left many families anxious about losing the vital support they rely on to keep their homes. Advocacy efforts are underway to protect these essential services, emphasizing their critical role in supporting families and preventing homelessness.
In real-life situations, housing counselors have stepped in as lifelines for families, guiding them through the often overwhelming challenges of homeownership, especially for those without legal help. Without this support, families may find themselves navigating a challenging path alone, risking their homes and futures.
The guarantee of quality associated with HUD-approved reverse mortgage counselors is essential for homeowners contemplating alternative financing options. It not only grants access to reliable information but also aids in safeguarding against deceptive practices, ensuring that families can make knowledgeable choices about their economic futures.
Enhanced Financial Literacy: Understanding Reverse Mortgages Through Expert Counseling
Navigating the world of home equity conversion loans can feel daunting, especially when it comes to planning for retirement. With professional guidance, individuals can gain a clearer understanding of how these loans work, the different types available, and their impact on retirement planning. We focus on helping you understand essential concepts in simple terms, so you feel confident in your choices.
Research shows that most homeowners who learn about alternative financing options believe these can provide crucial cash flow during retirement and offer more financial freedom. However, many seniors feel lost and overwhelmed when it comes to understanding their financial options, leaving them vulnerable in their retirement years. This gap shows how vital counseling is in helping seniors feel secure and informed about their financial choices.
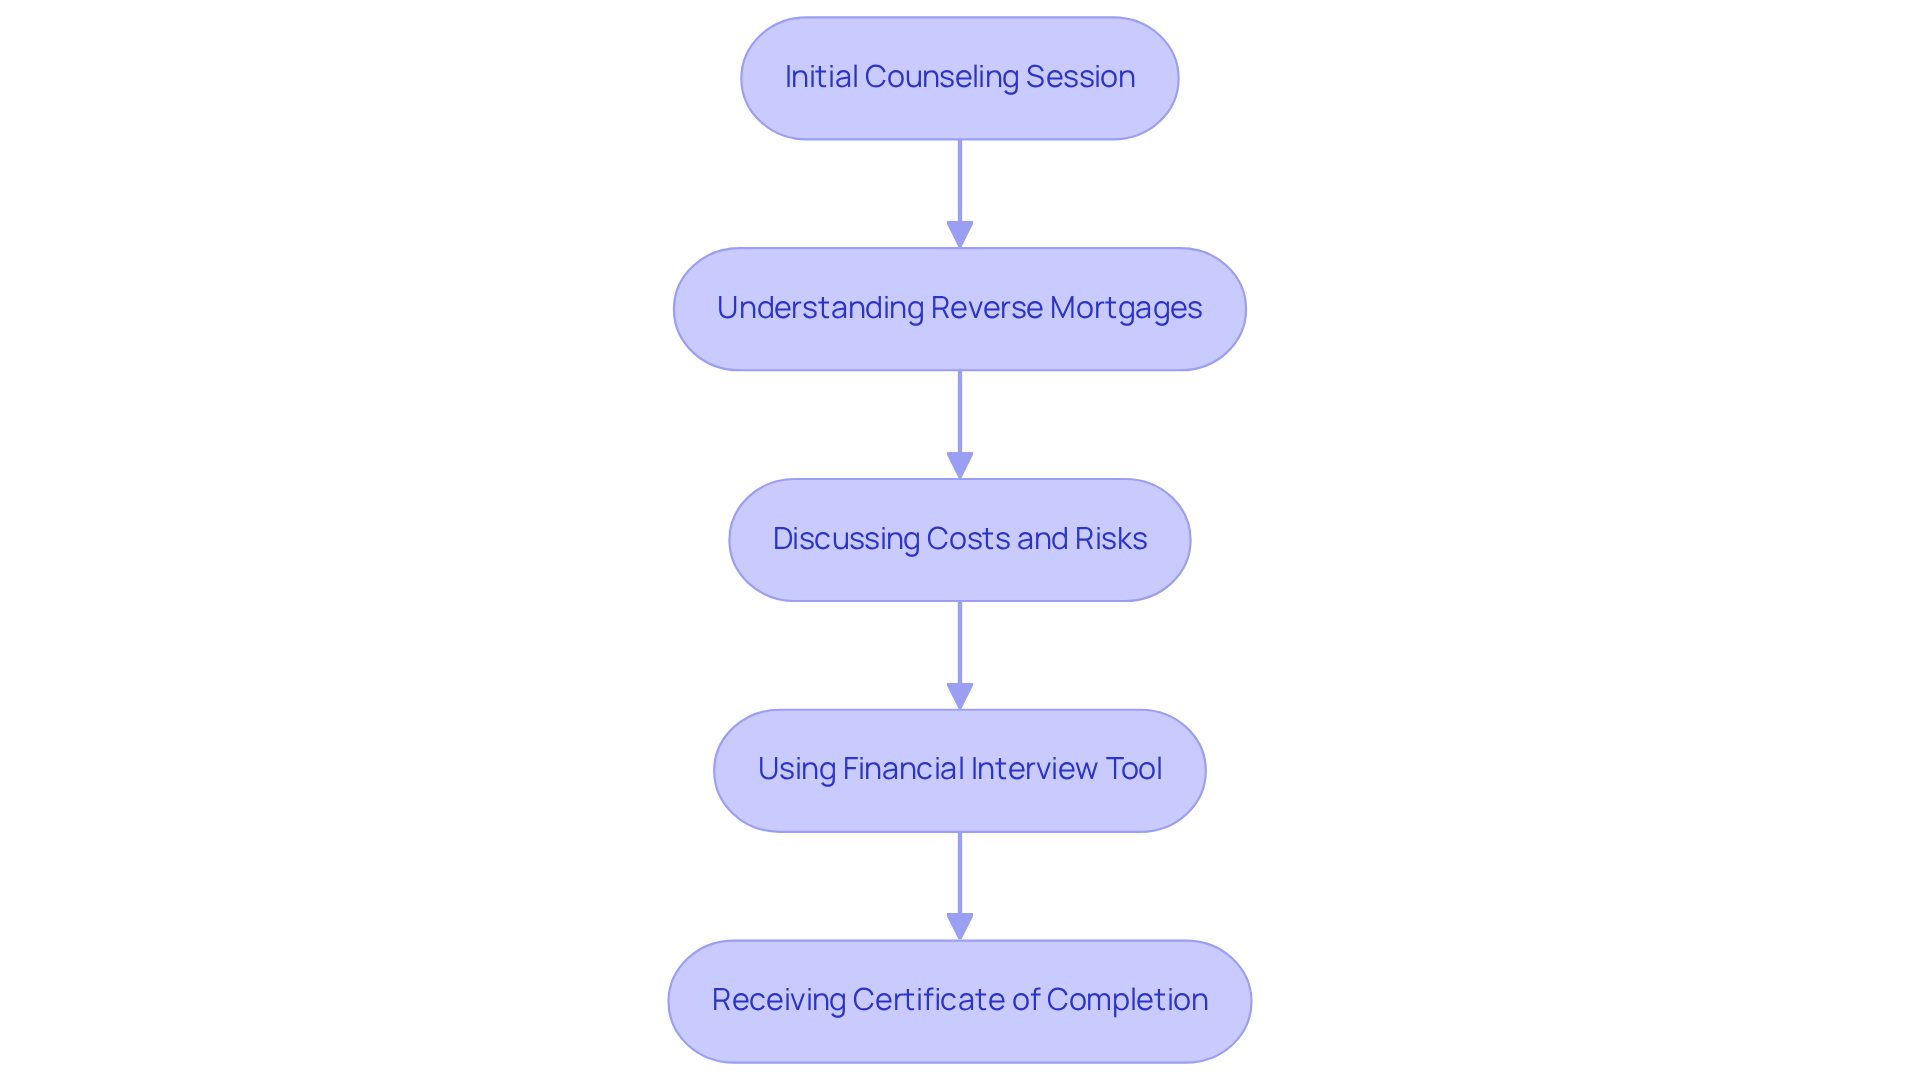
Mandatory counseling sessions with HUD-approved reverse mortgage counselors aim to educate individuals about the costs, risks, and advantages of reverse mortgages. These sessions typically last one to two hours and can be conducted over the phone or in person. At the conclusion of the session, participants receive a certificate verifying their completion of the required education, which is necessary for lenders to move forward with the loan application.
Case studies illustrate the effectiveness of this counseling. For example, during a session, counselors may utilize a Financial Interview Tool to customize discussions to individual monetary situations, improving the overall effectiveness of the counseling. This tailored method guarantees that clients comprehend their choices without being directed toward a particular offering, ultimately assisting in making well-informed choices regarding home equity conversion loans.
As wealth advisors increasingly acknowledge the importance of integrating home equity into retirement strategies, the acceptance of alternative loans as a practical resource continues to expand. Indeed, 61% of homeowners informed about reverse mortgages think they can assist in covering long-term care costs, further reinforcing the case for their growing acceptance among advisors. With the right support, seniors can confidently explore their options and secure a more stable financial future.
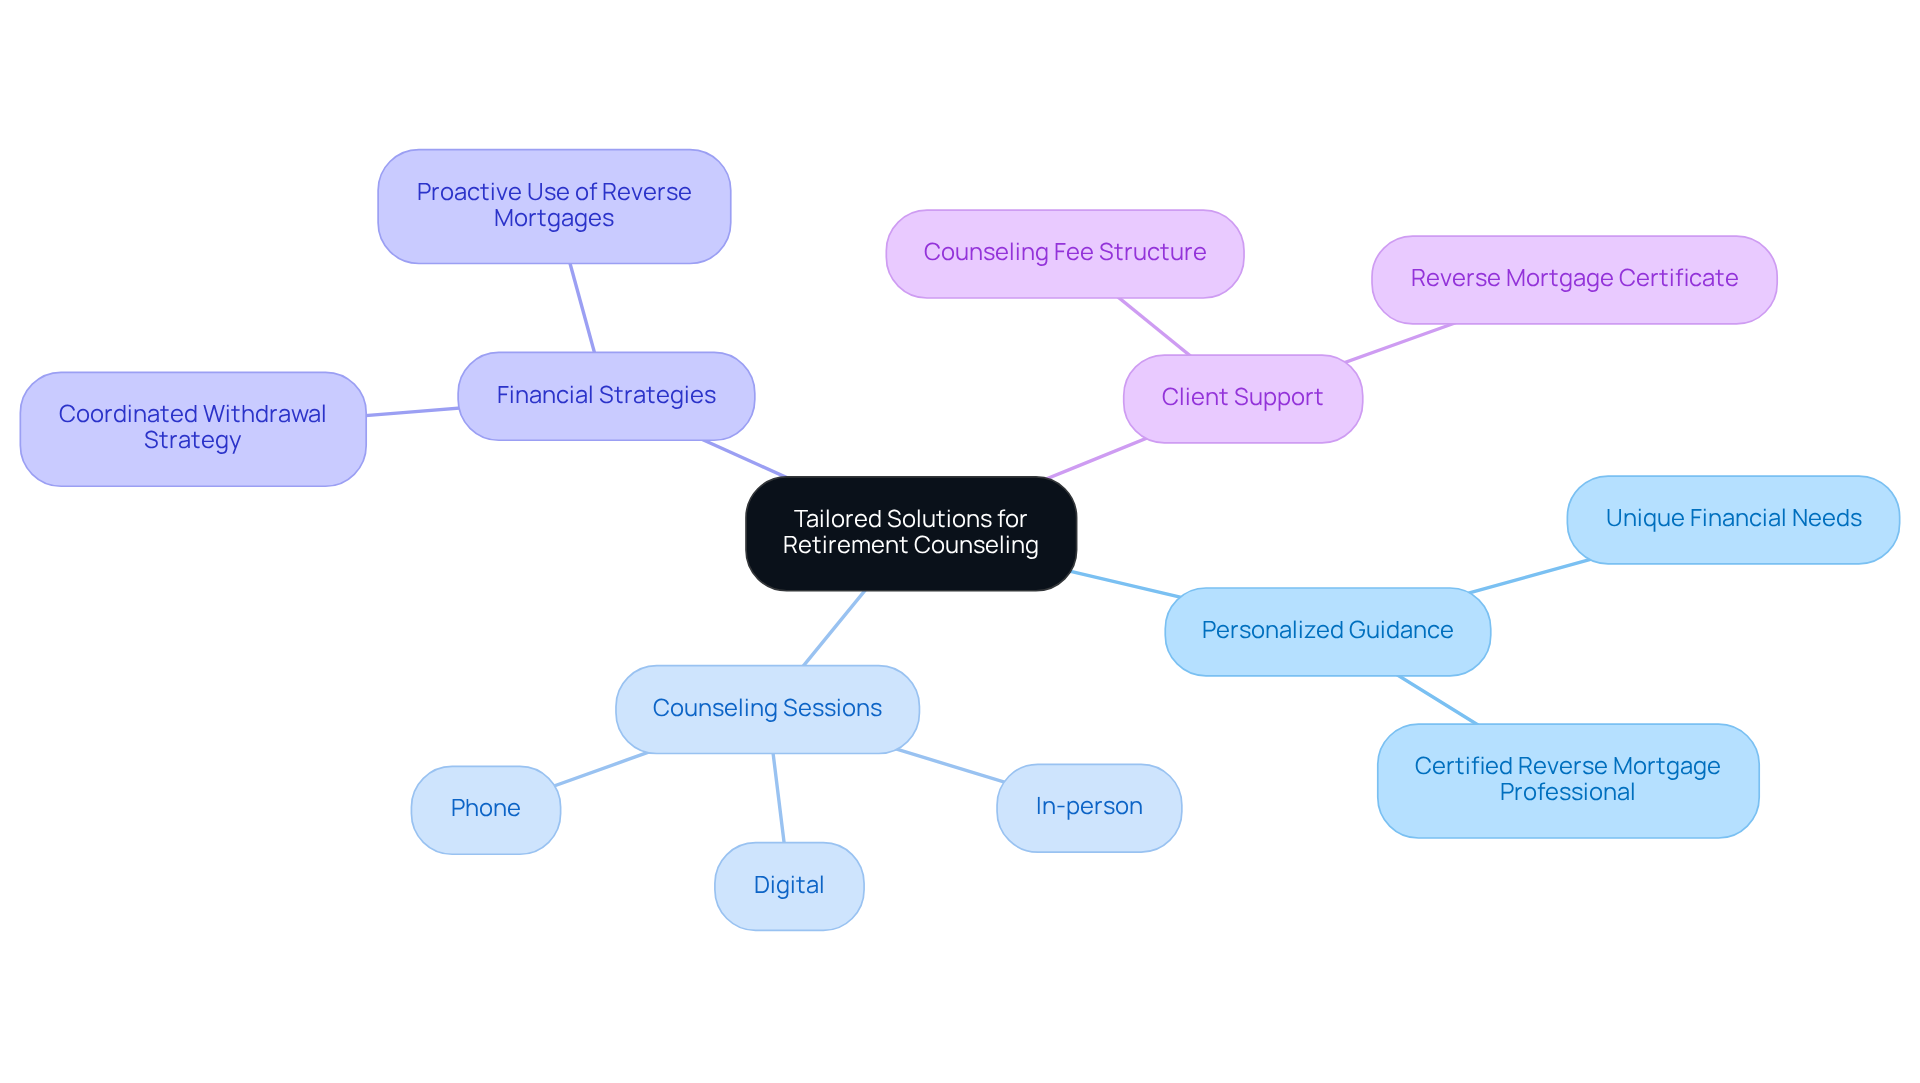
Tailored Solutions: Customized Counseling for Individual Needs
Navigating financial decisions in retirement can feel overwhelming, especially when every choice seems so significant. We understand that every client has unique financial needs, and we’re here to provide personalized guidance that truly resonates with your situation. As a Certified Reverse Mortgage Professional, I specialize in helping retirees in Boca Raton secure the right loan product for their needs. My commitment to excellent customer service means you can relax knowing you are in good hands throughout the process.
If you’re thinking about a Home Equity Conversion Mortgage (HECM), we want you to know that counseling sessions are an important step to ensure you feel supported and informed. These sessions can be conducted in person, digitally, or over the phone, and typically last about one hour. Upon completion, you will receive a Reverse Mortgage Certificate, valid for 180 days, which is necessary to proceed with your application.
We believe that everyone should have access to essential counseling services, which is why the typical fee of $175 can be waived for those with lower incomes, easing any financial burden. In a study analyzing withdrawal methods, retirees who actively utilized a home equity line of credit during market declines achieved notably improved outcomes, with one retiree ending up with a portfolio value exceeding $1.5 million compared to those depending solely on portfolio withdrawals. This proactive method enabled them to safeguard their investment capital, illustrating the importance of customized monetary strategies.
Furthermore, HUD-approved reverse mortgage counselors can help you explore various options and understand the implications of each choice. This personalized guidance is crucial for making informed decisions that align with your retirement goals. With the right guidance, you can take control of your financial future and find the peace of mind you deserve.
Navigating Complexity: Expert Guidance Through the Application Process
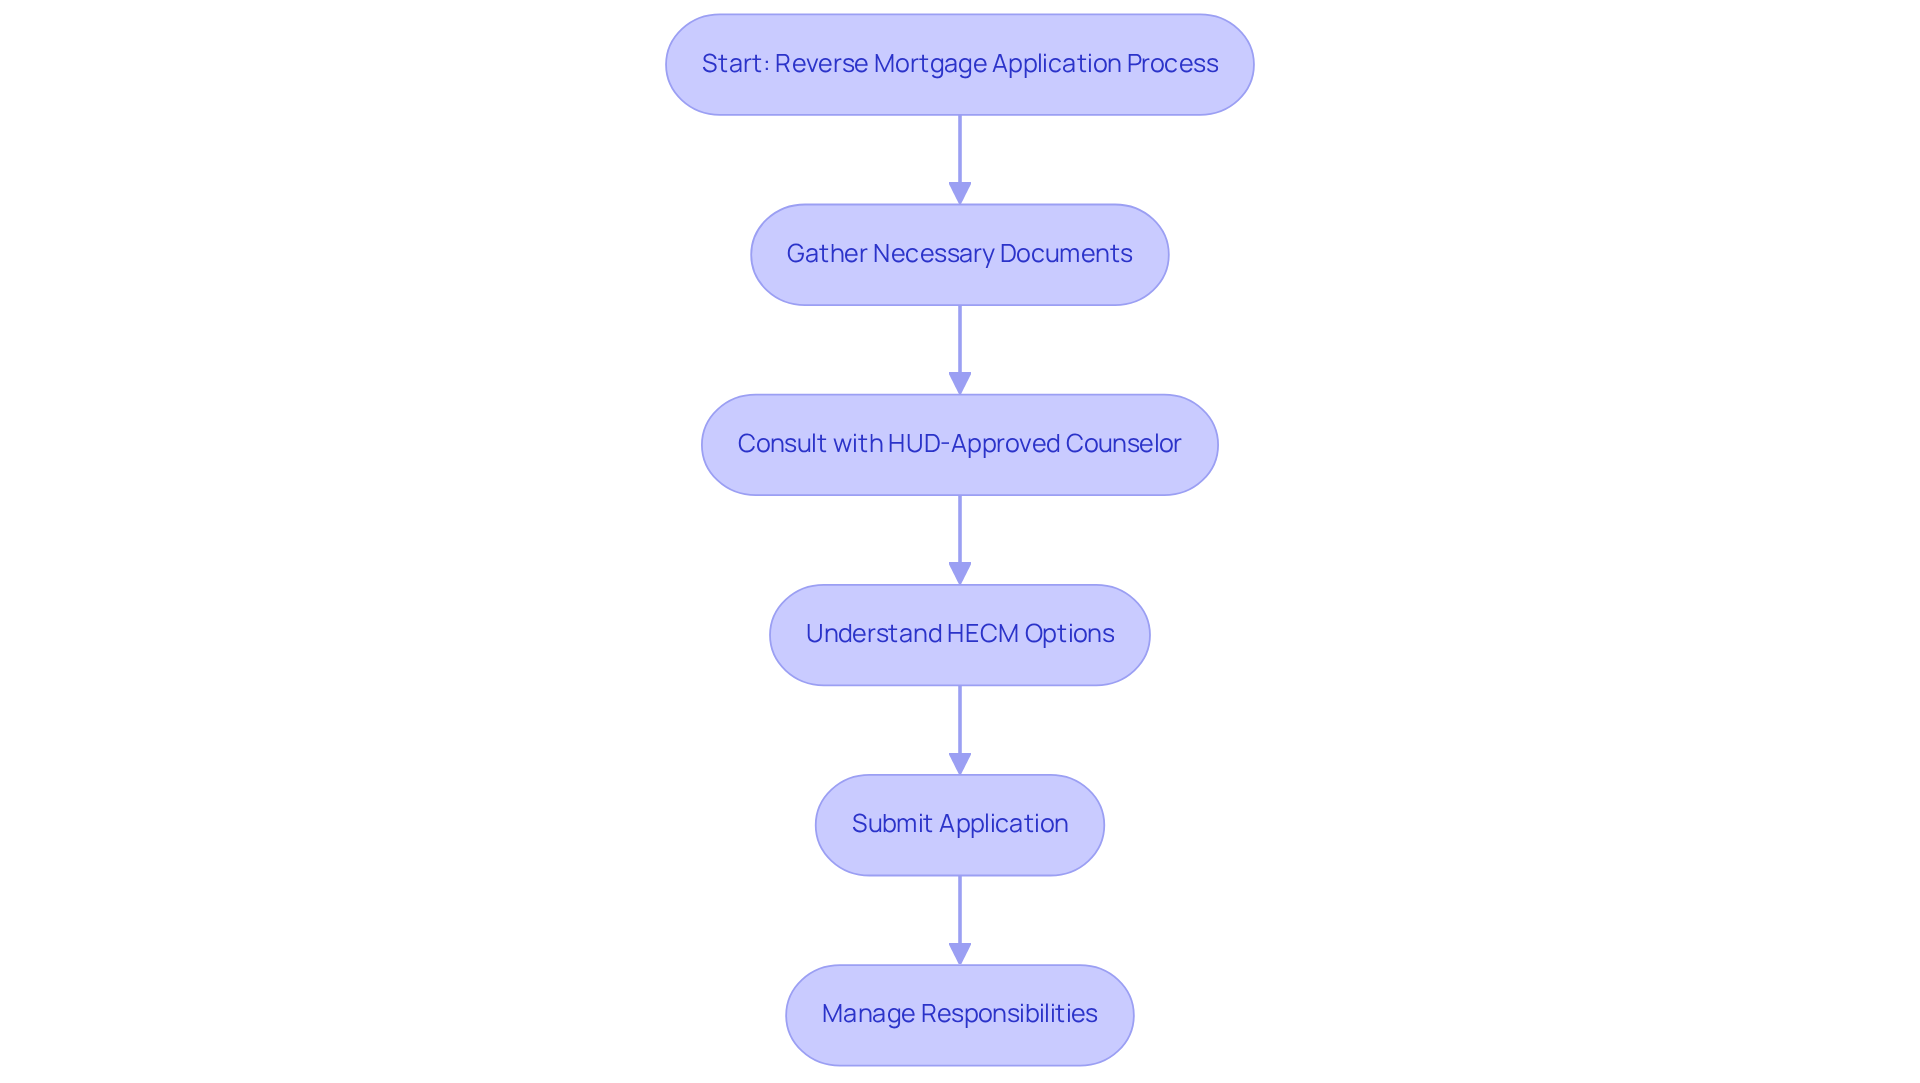
Navigating the reverse mortgage application process can feel daunting, especially when faced with so many steps and requirements. It’s not uncommon for seniors to feel overwhelmed by the paperwork and deadlines involved in the application process. I’m here to walk you through each step, making sure you know exactly what to expect along the way.
With the right support, you can feel confident and empowered to make the best financial decisions for your future. Collaborating with HUD-approved reverse mortgage counselors can assist you in navigating these complexities, ensuring you make informed choices that truly fit your needs.
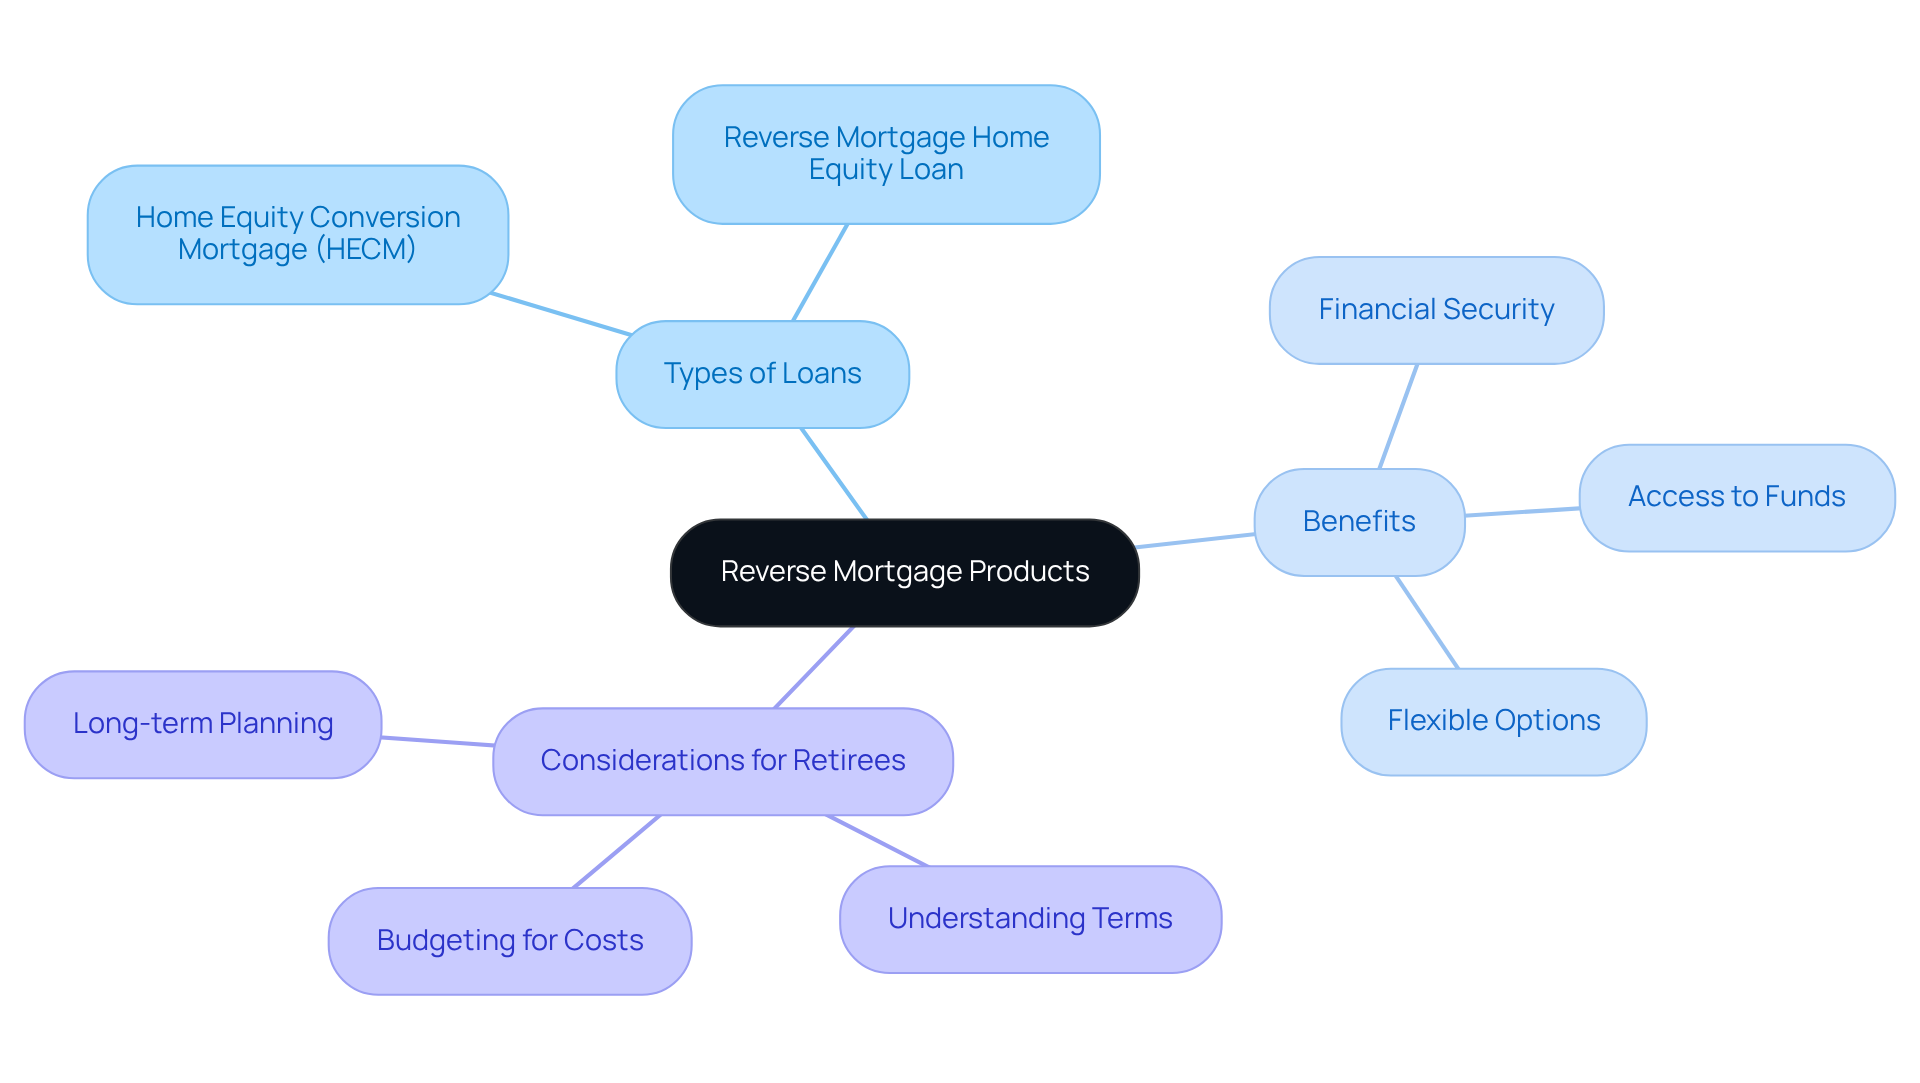
A Home Equity Conversion Mortgage (HECM) is a special type of loan that lets you access some of your home’s equity, giving you options like cash upfront, a line of credit, or monthly payments. Remember, you’ll still need to keep up with important responsibilities like property taxes and homeowners insurance, but I’m here to help you understand how to manage these alongside your loan.
If you’re thinking about a home equity conversion loan, please reach out. We’re here to provide personalized comparisons and help you find the best fit for your situation.
Ongoing Support: Building a Long-Term Relationship with Your Counselor
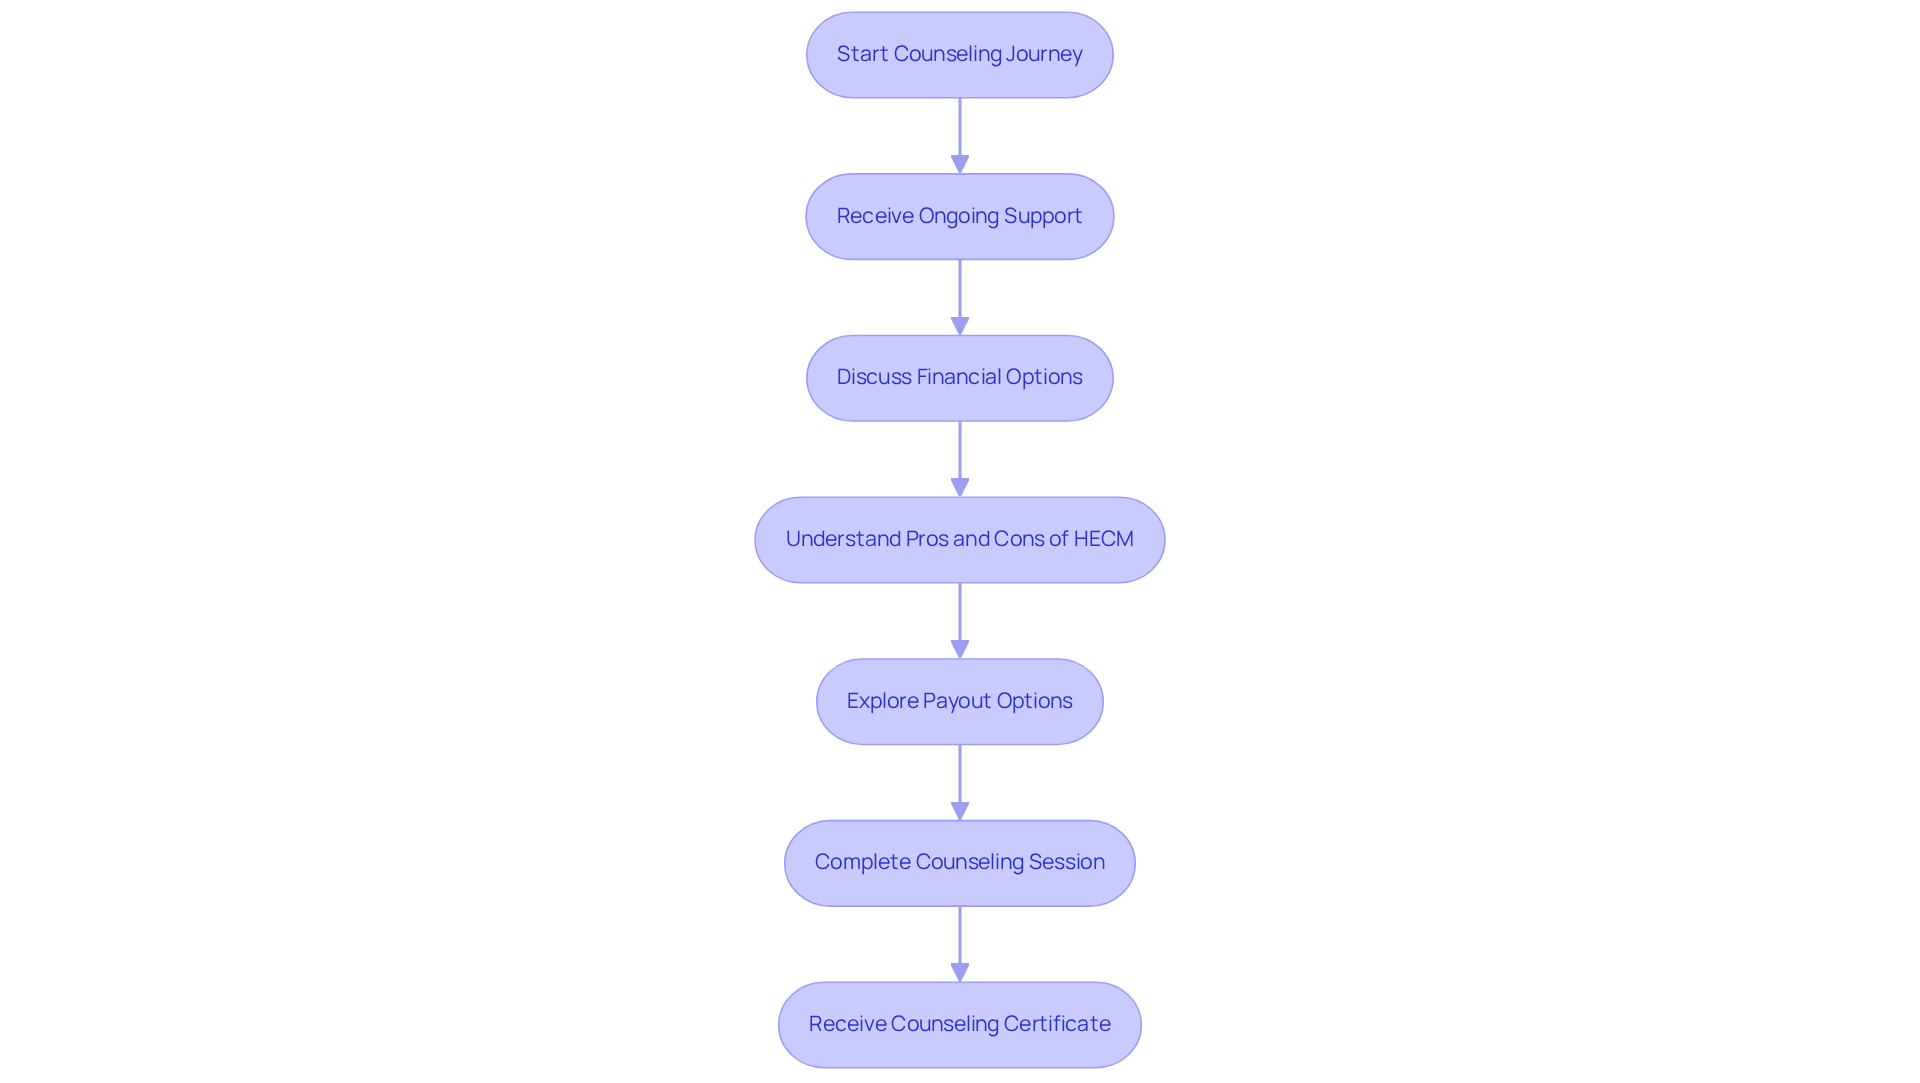
Starting the counseling journey means opening the door to ongoing support and understanding. I’m here to provide continuous assistance, ensuring you have guidance as your financial situation evolves. Whether you have questions about your home equity loan or need help with upcoming financial decisions, you’re not alone in this process.
Recent findings reveal that many older adults are facing financial challenges as they explore alternative financing options. About 21.1% of older adults pursuing home equity conversion loans reported a monthly budget shortfall. This highlights the need for advisors to help individuals explore their options and make informed choices regarding their Home Equity Conversion Mortgage (HECM).
Hud-approved reverse mortgage counselors are here to help you understand the pros and cons of reverse mortgages and connect you with valuable resources. With various payout options available – like a line of credit, cash out, term payments, or tenure payments – I assist you in seeing how these funds can be used in flexible ways to support your needs, whether it’s for home improvements, in-home care, or boosting your retirement savings. This approach helps you clarify your financial goals and understand the impact of your choices. The counseling process is designed to protect you, focusing on education rather than sales.
Counseling sessions typically last 1-2 hours and conclude with a counseling certificate, which is essential for lenders to process loan applications. This certificate confirms that you’ve received the necessary education to make informed choices about your financial future. If your income is below 200% of the Federal Poverty Guidelines, the initial charge for counseling can be postponed until the loan closing. Having a dedicated home equity counselor by your side can make all the difference as you navigate your financial journey.
Peace of Mind: Confidence in Your Counseling Relationship
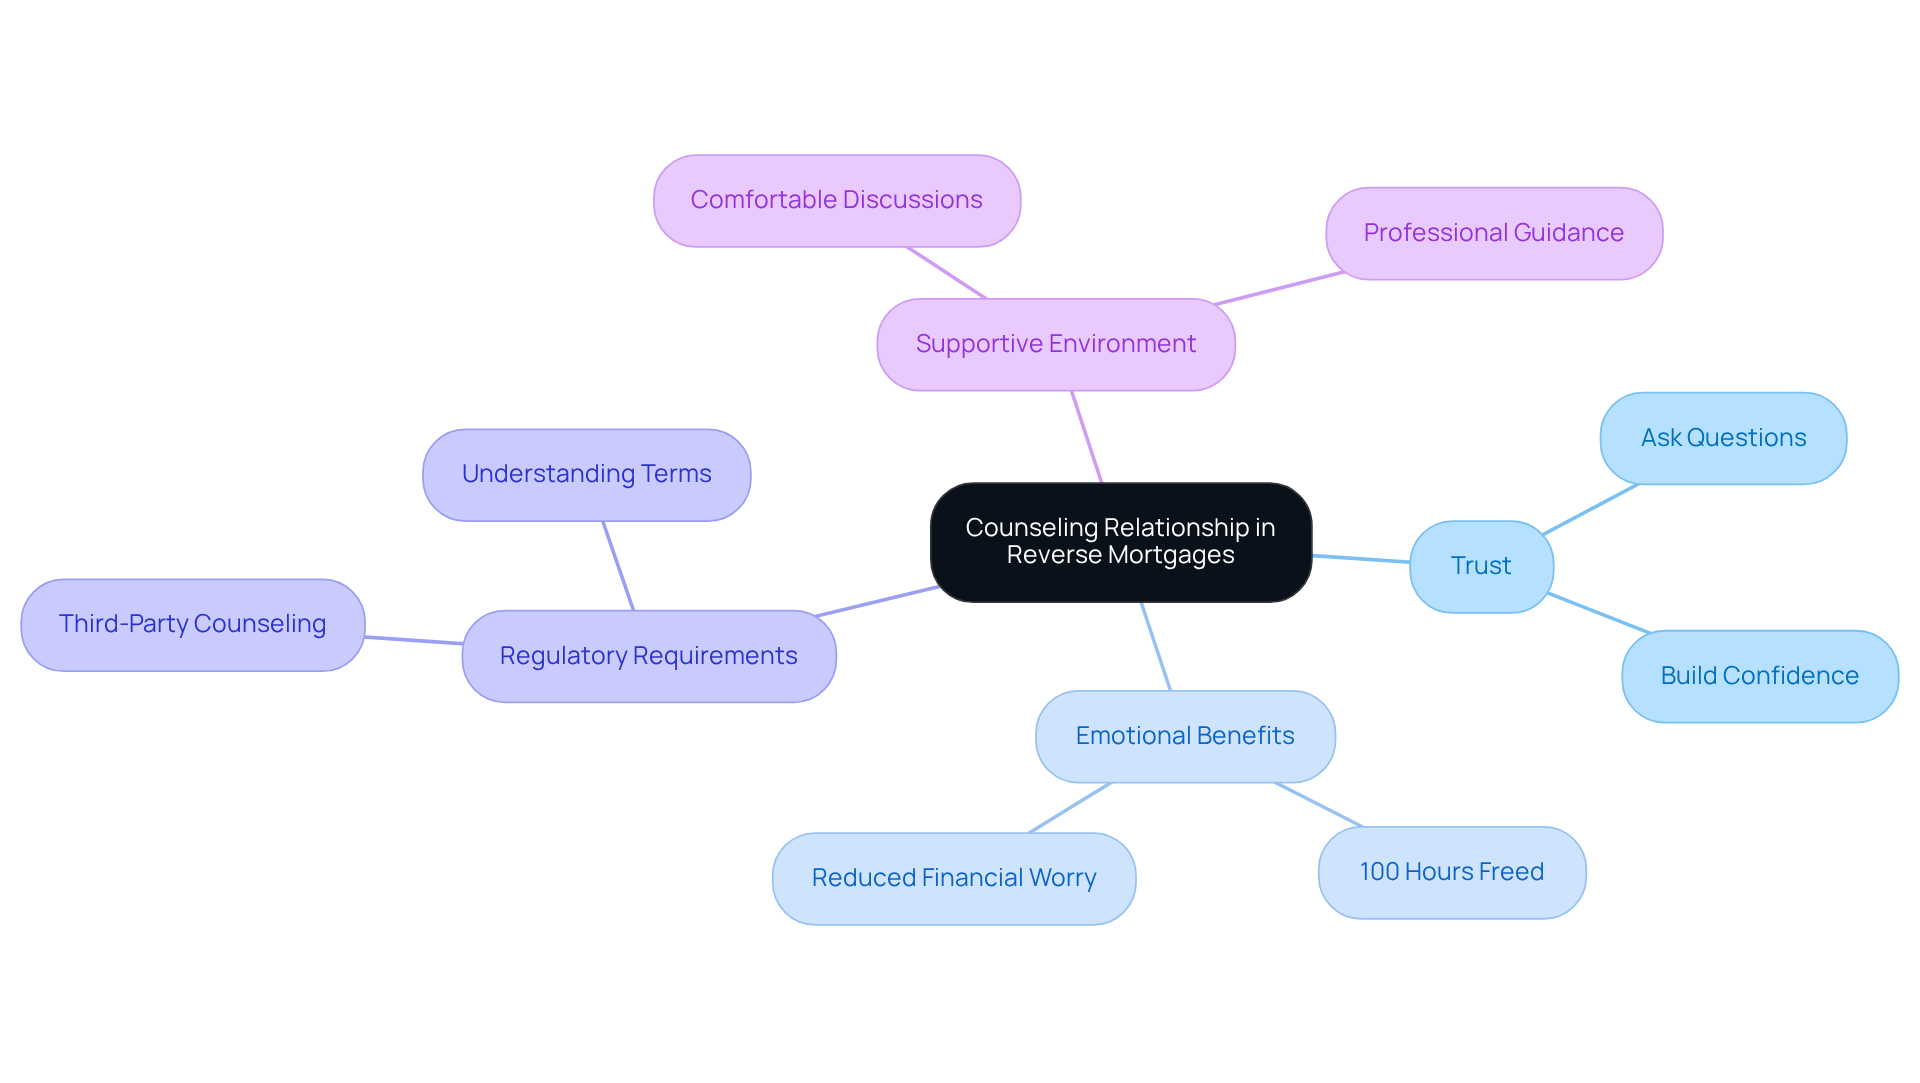
Navigating the complexities of reverse mortgages can feel daunting, but having HUD-approved reverse mortgage counselors by your side can truly make all the difference. I strive to create a supportive environment where you can comfortably ask questions and express concerns. This trust in our counseling relationship enables you to make well-informed choices regarding your economic future without unnecessary pressure.
Studies show that when clients receive financial guidance, they worry less about money, freeing up over 100 hours a year for family and personal interests. When you have a trusted advisor, it’s amazing how much lighter your financial worries can feel. This reduction in stress is a testament to the emotional benefits of having someone by your side.
Case studies show that many older homeowners are utilizing home equity loans not only to remove current loan payments but also to adapt their residences for aging, a process referred to as age-proofing. This approach highlights how home equity loans can help you make your home more comfortable as you age in place.
Furthermore, the requirement for third-party counseling from HUD-approved reverse mortgage counselors ensures that you fully understand the terms and responsibilities associated with reverse mortgages. This regulatory action, implemented following the 2008 economic downturn, seeks to mitigate risks and bolster borrower trust. As a result, you can feel secure knowing that your decisions are informed and backed by professional guidance.
In summary, the relationship you build with your counselor is crucial. It fosters trust and clarity, allowing you to navigate your options with confidence. With the right support, you can turn uncertainty into confidence, knowing you have a partner in your financial journey.
Informed Choices: Access to Comprehensive Knowledge of Reverse Mortgage Products
Navigating the world of home equity loans can feel overwhelming, especially when financial pressures are mounting. Many seniors are feeling the pinch of rising costs, struggling to make ends meet each month. By 2025, a significant number of older adults pursuing a home equity loan may find themselves facing budget shortfalls, highlighting the need for understanding the benefits of each option available to you.
As you explore these choices, you can find the home equity conversion option that best meets your needs. For instance, exclusive home equity loans can be particularly beneficial for homeowners with high property values that exceed FHA’s maximum loan limit. It’s more important than ever to understand the benefits of each option available to you, as many homeowners are increasingly viewing alternative financing as a way to secure their financial future rather than just a tactical tool.
As these changes unfold, it’s essential for advisors to understand alternative home equity loans to better support their clients. I’m here to share valuable information about alternative financing products that can help you navigate these options with confidence, ensuring that you can make choices that enhance your overall well-being. By understanding your options, you can take control of your financial future and find peace of mind in your retirement years.
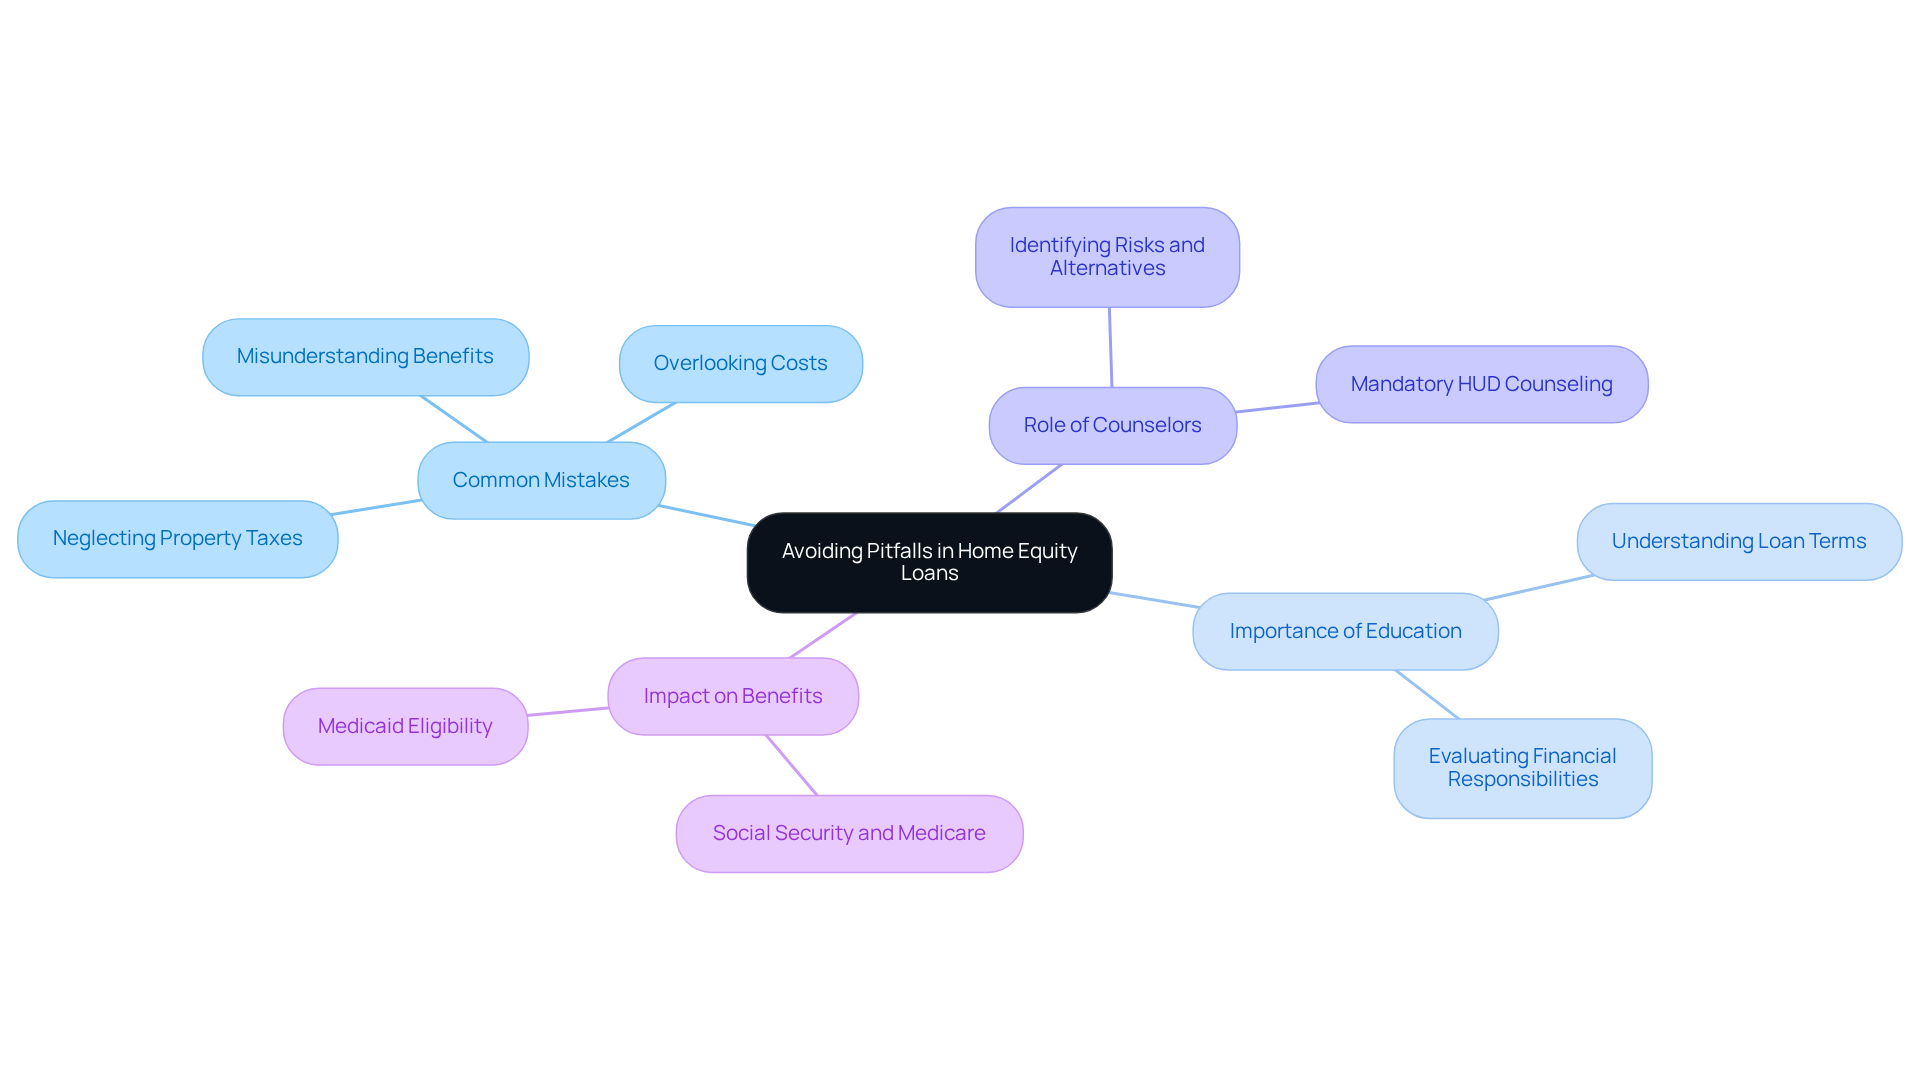
Avoiding Pitfalls: Expert Advice to Prevent Common Mistakes
Navigating home equity loans can feel overwhelming, especially when the stakes are so high for seniors and their families. Many borrowers struggle with misunderstandings about loan terms and often overlook important costs. These mistakes can lead to unexpected financial burdens that weigh heavily on families. Indeed, neglecting to pay property taxes and homeowners insurance can lead to the loss of your home, turning a dream of financial security into a nightmare of foreclosure.
We understand that avoiding these pitfalls starts with education and thoughtful planning. Interacting with HUD-approved reverse mortgage counselors for home equity loans can provide essential understanding of these financial products, ensuring that borrowers are fully aware of their responsibilities. For example, the Life Expectancy Set Aside (LESA) can be a crucial tool for protecting against defaults by reserving funds for property charges.
Furthermore, many older homeowners incorrectly think that securing a loan against their home will adversely affect their Social Security or Medicare benefits. However, it’s crucial to clarify that home equity conversion loan proceeds are regarded as loans, not income, and typically do not influence these benefits. Yet, they can impact need-based assistance like Medicaid if not managed properly.
Case studies emphasize the significance of awareness: borrowers who neglect to evaluate all expenses related to reverse mortgages, including high fees and fluctuating interest rates, frequently find themselves in unstable economic situations. By sharing these common errors, we empower you to make informed choices that protect your financial interests, allowing you to enjoy your retirement without added stress.
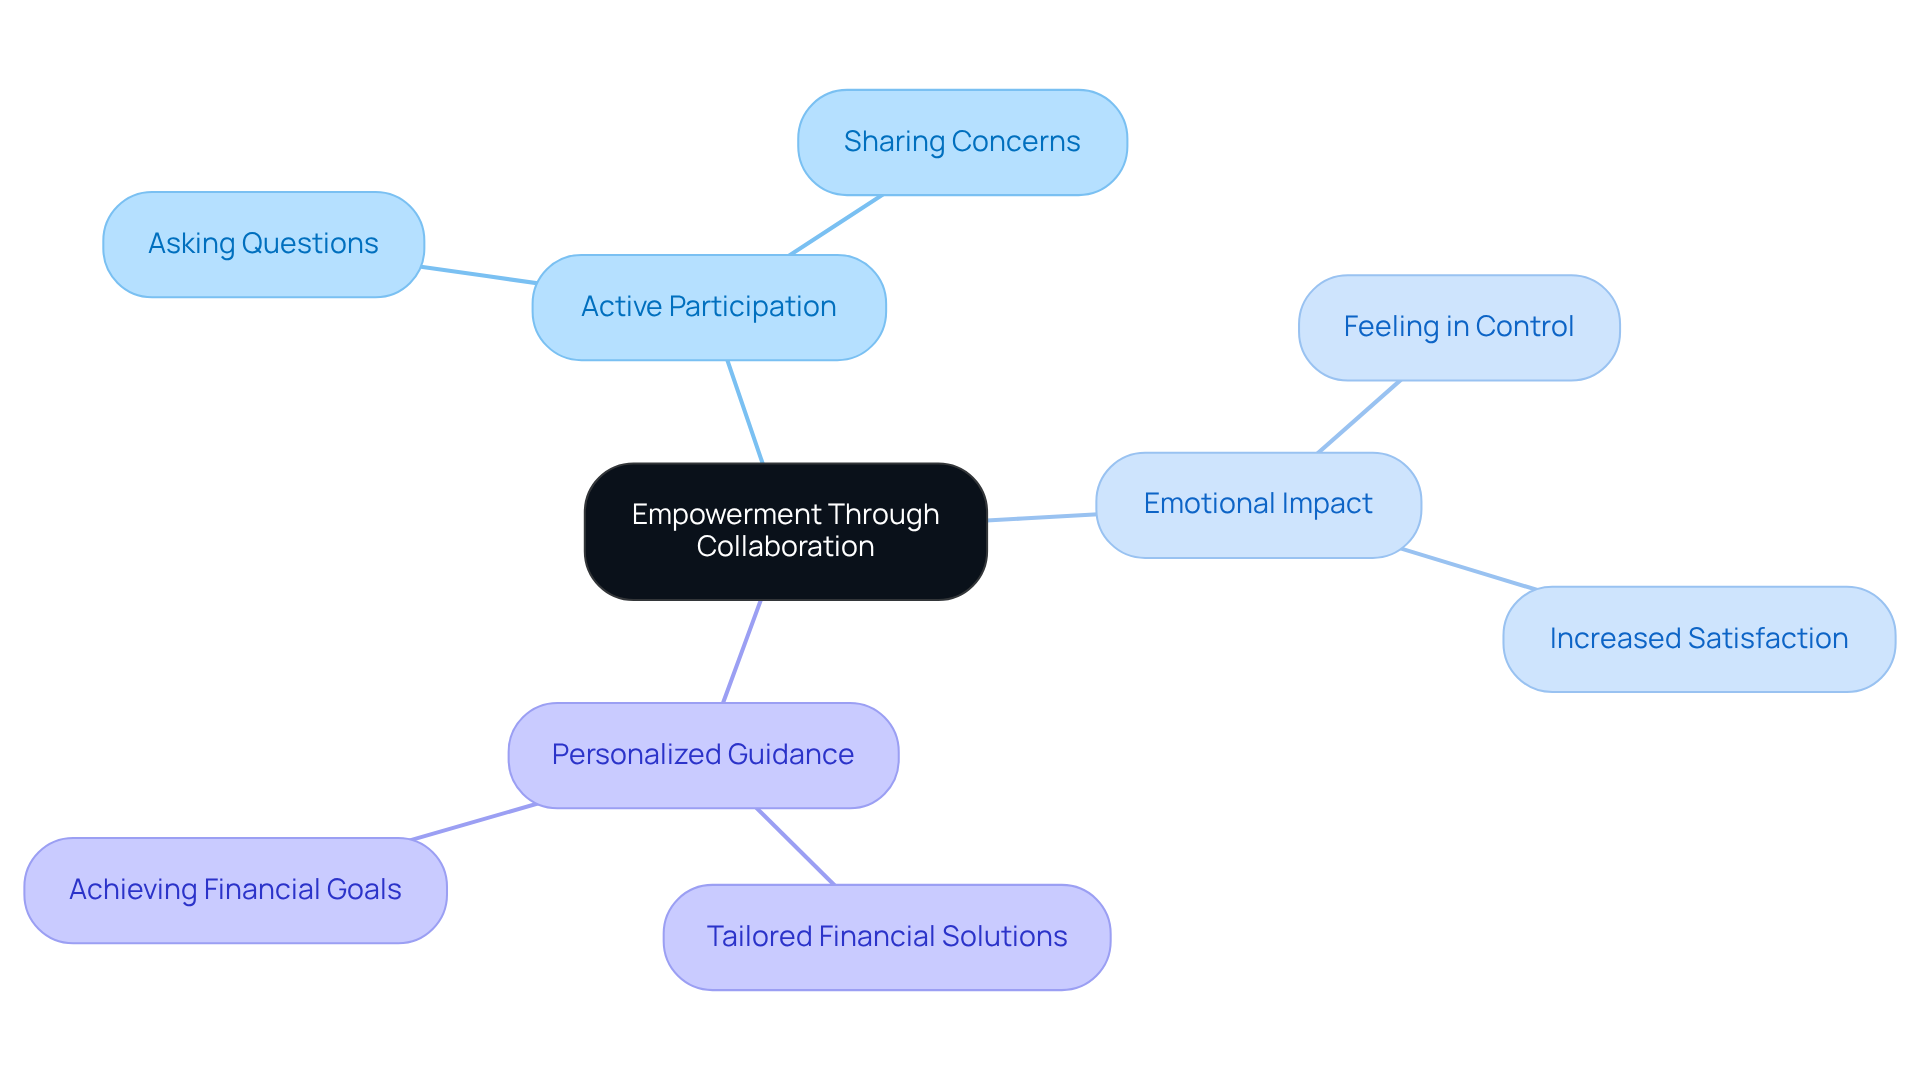
Empowerment Through Collaboration: Engaging in Your Financial Future
We understand that working together is key to effective counseling, and it can make a world of difference in your journey. I encourage my clients to actively participate in the process by asking questions and sharing their concerns. This collaborative approach empowers you to take charge of your financial future with confidence. When you actively participate in your financial counseling, you’re likely to feel more satisfied and in control of your choices.
By creating a space where you feel comfortable discussing your needs and preferences, I ensure you feel assured in your decisions regarding reverse mortgages and your overall retirement planning. Engaging in this way leads to a more enriching experience, ultimately enhancing your financial well-being.
Insights from finance specialists show that your involvement is crucial for achieving successful outcomes, as it allows for personalized guidance that meets your unique needs. Moreover, case studies reveal that clients who work closely with their counselors are more likely to reach their financial goals, highlighting the emotional impact of partnership in the counseling process.
Conclusion
Many seniors find themselves feeling lost and overwhelmed when it comes to understanding reverse mortgages, but there’s help available. Working with HUD-approved reverse mortgage counselors means having caring professionals by your side, guiding you through the complexities and helping you feel informed and confident about your financial choices.
Throughout this article, we’ve highlighted the key benefits of engaging with these counselors. They enhance your financial literacy, provide tailored solutions, and support you through the application process. Knowing that these counselors are HUD-approved gives you peace of mind, reinforcing the value of their expert guidance.
The path to financial security in retirement is much smoother when you have knowledgeable friends by your side. By choosing to work with HUD-approved reverse mortgage counselors, you can gain clarity and feel empowered to shape your financial future with confidence.
Frequently Asked Questions
What is a reverse mortgage?
A Home Equity Conversion Mortgage (HECM)-commonly known as a reverse mortgage-is an FHA-insured loan that allows eligible homeowners to access a portion of their home equity through a cash lump sum, line of credit, monthly payments, or a combination of these options.
Who can benefit from working with a Certified Reverse Mortgage Professional (CRMP)?
Homeowners aged 62 and older, as well as their adult children or financial advisors, can benefit from working with a CRMP. They provide personalized guidance and clear, unbiased information to help individuals make informed decisions about their retirement funding.
Why is HUD-approved counseling important for reverse mortgage borrowers?
HUD-approved counseling is essential because it provides homeowners with reliable information and guidance tailored to their unique situations. It helps protect against deceptive practices and ensures that families can make knowledgeable choices about their financial futures.
What types of reverse mortgage options are available?
The main options include FHA-insured Home Equity Conversion Mortgages (HECM), HECM for Purchase, and other retirement mortgage programs.
How long do mandatory counseling sessions typically last?
Mandatory counseling sessions with HUD-approved reverse mortgage counselors typically last one to two hours and can be conducted over the phone or in person.
What is the purpose of the Financial Interview Tool used in counseling sessions?
The Financial Interview Tool is used to customize discussions to individual monetary situations, improving the overall effectiveness of the counseling and ensuring clients understand their options without being directed toward a specific product.
How can reverse mortgages assist in retirement planning?
Research shows that many homeowners believe reverse mortgages can provide crucial cash flow during retirement and offer more financial freedom. They can help cover long-term care costs and integrate home equity into retirement strategies.
What protections do heirs have when a reverse mortgage is in place?
Heirs benefit from several protections: FHA-insured HECM loans are non-recourse, meaning heirs never owe more than the home’s value; independent HUD counseling is required; and family members are encouraged to participate in the decision-making process regarding the home.
Have questions about this?
Talk to a Certified Reverse Mortgage Professional — directly.
When you call, you reach me — not a call center. Free 30-minute consult by phone, video, or in person. No SSN, no credit pull, no obligation.
Schedule a consult