

Reverse Mortgage FAQs
Master the Reverse Mortgage Calculator Without Personal Information
Introduction
Many retirees feel overwhelmed when it comes to understanding their financial options, especially regarding their home equity. A Home Equity Conversion Mortgage (HECM) – an FHA-insured loan – offers a unique opportunity for eligible homeowners to tap into their home equity without the burden of monthly payments.
We’ll explore how reverse mortgage calculators can help you feel more empowered in your financial journey. But what if those numbers bring up more than just potential equity? What if they stir up feelings of uncertainty or fear? How can you interpret these estimates to feel secure and confident in your financial future?
Define Reverse Mortgages and Their Purpose
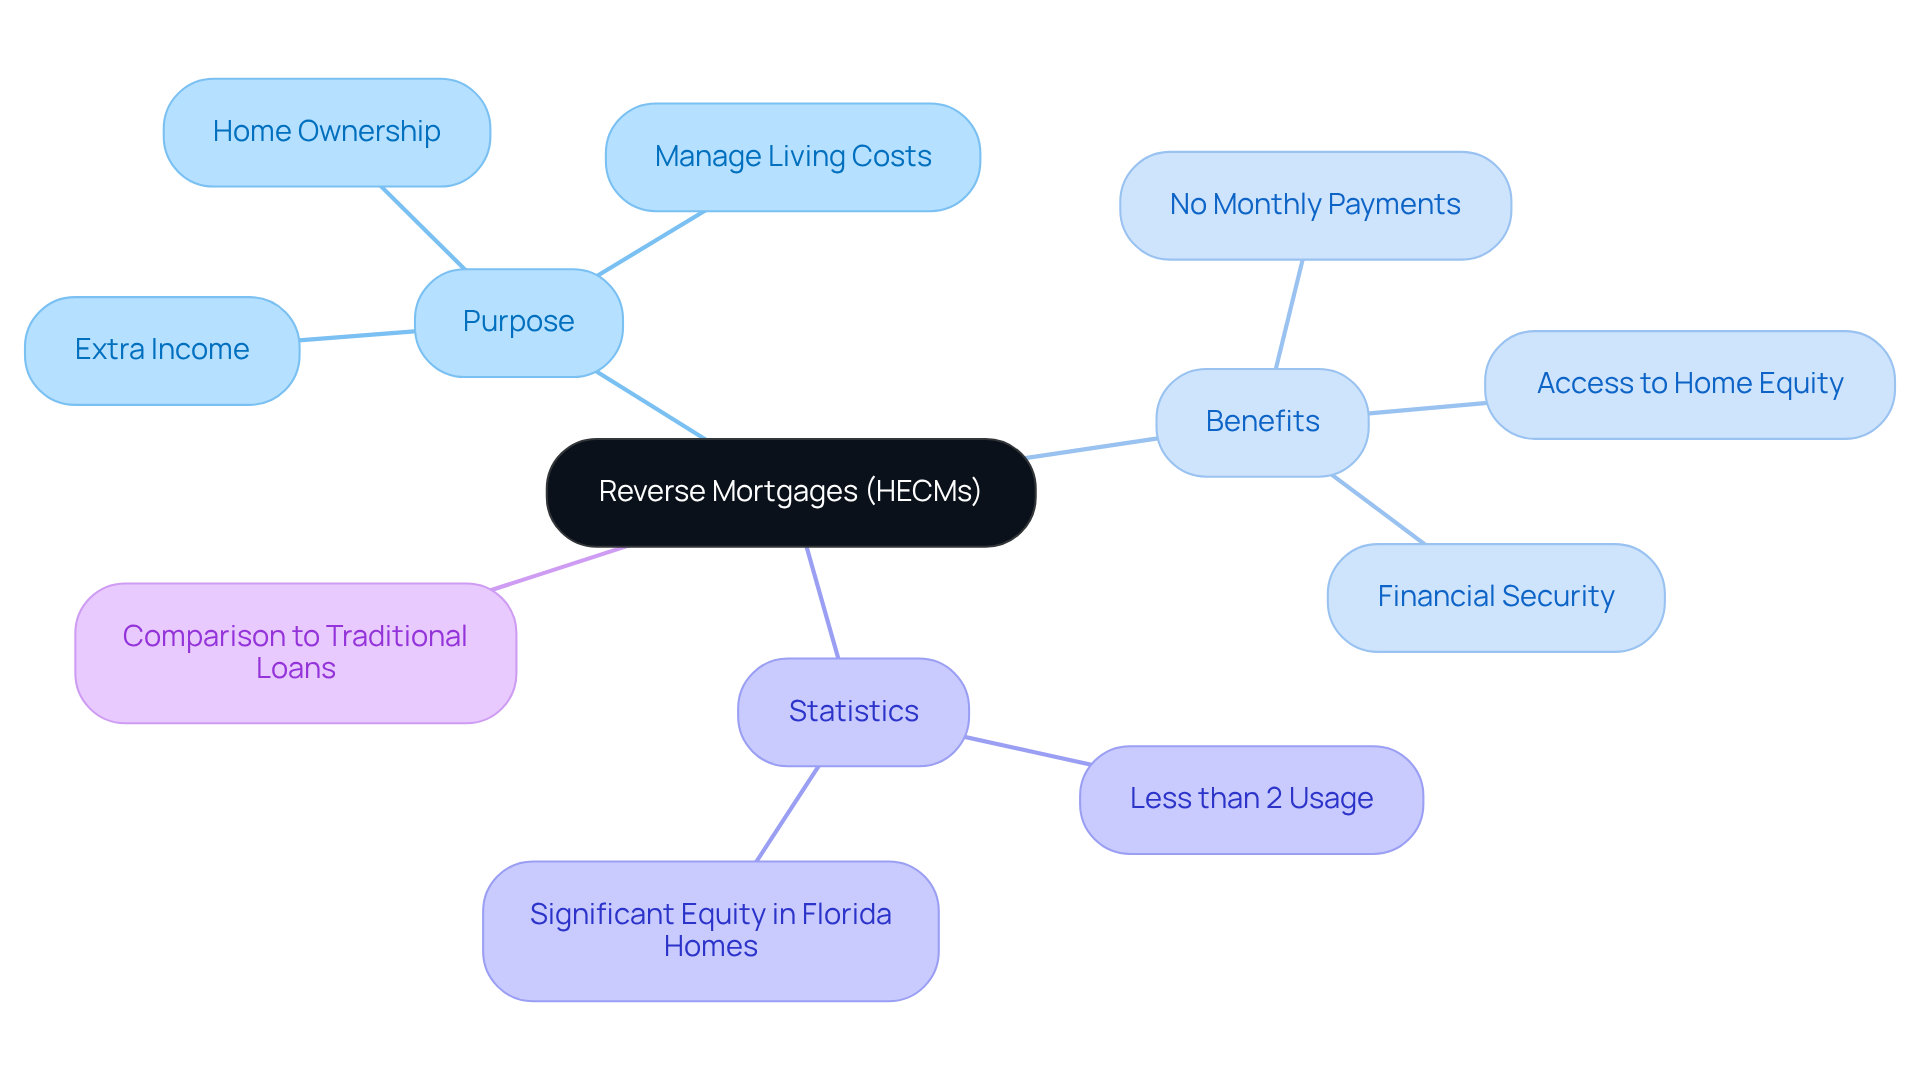
Many retirees face financial challenges that can feel overwhelming, especially when it comes to managing their living expenses and healthcare costs. A Home Equity Conversion Mortgage, or HECM, is a special type of loan insured by the FHA. It allows homeowners to tap into their home equity in various ways, like receiving a cash lump sum, a line of credit, or monthly payments. The goal of this financial option is to provide retirees with extra income during retirement, helping them manage living costs, healthcare expenses, or even renovations without the stress of monthly payments. Importantly, the borrower keeps ownership of the property, and the loan is only due when the last borrower permanently leaves the home, sells the property, or passes away.
Despite the benefits, fewer than 2% of retired households utilize reverse financing options. This shows that many retirees might be missing out on a valuable opportunity to improve their financial security and enjoy their retirement more fully. In Florida, where the population includes a diverse mix of retirees and younger residents, many older homeowners have significant equity in their homes. With a median property price of $415,762 in 2022, retirees in Florida could greatly benefit from tapping into their home equity to enhance their financial situation.
Recent trends indicate that many older adults are opting for conventional loan products that require monthly payments, which can be financially challenging during retirement. Unlike traditional loans, HECMs allow retirees to access their home equity without the burden of monthly payments, making it easier for them to maintain their lifestyle during retirement. Understanding HECMs could be the key to unlocking a more secure and fulfilling retirement for many seniors.
Explain How the Reverse Mortgage Calculator Works
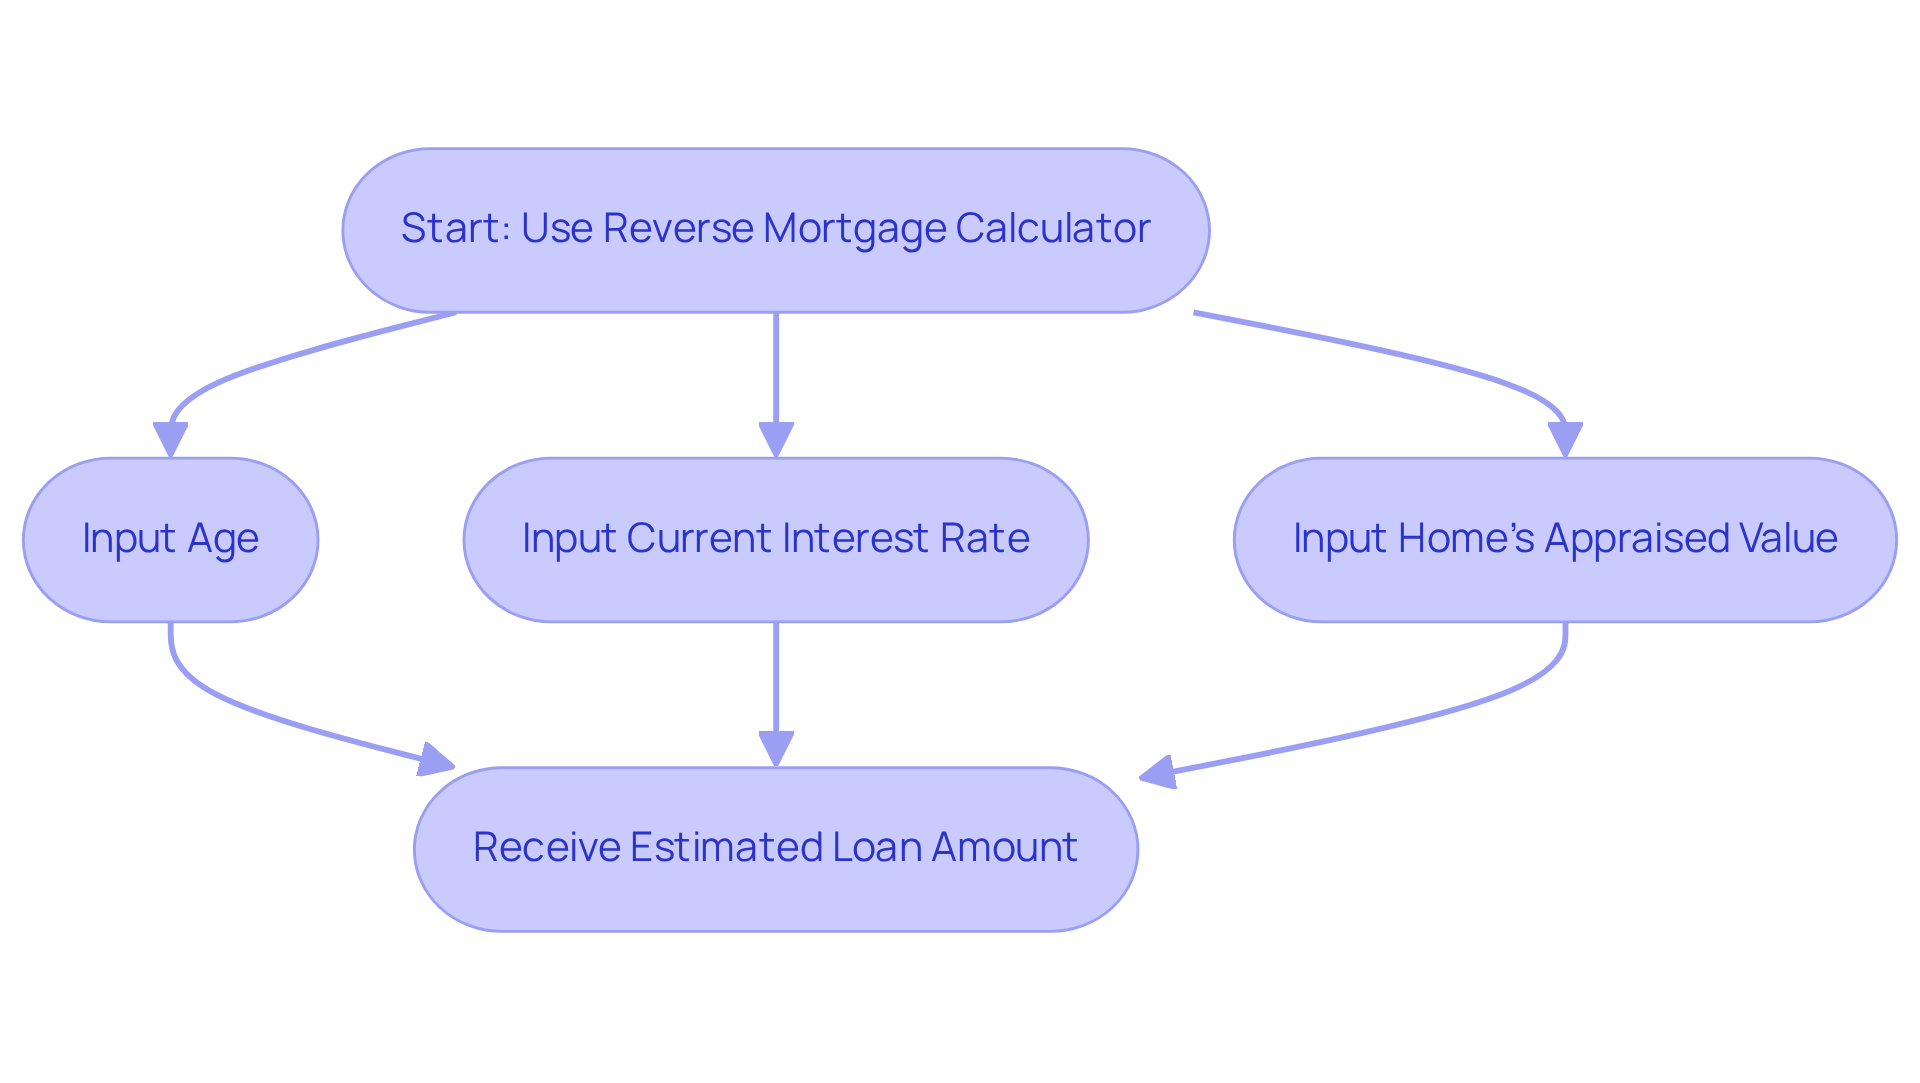
Navigating financial options can feel overwhelming, especially when it comes to understanding how much equity you can access through a Home Equity Conversion Mortgage (HECM). The reverse mortgage calculator is a user-friendly tool designed to help you estimate that equity. By considering key factors like your age (and that of any eligible non-borrowing spouses), the current interest rate, and your home’s appraised value, this tool provides an instant estimate of your potential loan amount. You can explore these options without any pressure, keeping your personal information safe.
As interest rates are expected to gradually decline throughout 2025 and possibly into 2026, the benefits of using a home equity calculator become even more significant. Lower interest rates can reduce the interest buildup on your loan, making alternative financing a more affordable choice for retirees looking to boost their income. Many retirees face financial challenges due to rising expenses, and alternative home equity solutions can provide extra monthly income without requiring monthly repayments, depending on the loan terms and your situation.
Real-life examples show just how helpful these calculators can be. For instance, the HECM calculator gives a clear picture of the potential benefits available to those aged 62 and older. This tool supports your financial planning by clarifying your potential benefits. Additionally, the HECM for Purchase calculator helps you estimate the one-time down payment needed to buy a property using alternative financing, making your decision-making process smoother.
In general, a reverse mortgage calculator no personal information serves as a valuable resource for homeowners, allowing you to make informed choices about your financial future without needing to share personal details. It’s essential to remember that HECM borrowers are typically age 62 and older, with provisions for eligible non-borrowing spouses under 62. Understanding these tools can empower you to make informed decisions about your financial future, ensuring you’re not alone in this journey.
Identify Key Inputs for Accurate Calculations
Navigating the HECM calculator can feel daunting, especially when it comes to understanding your financial options in retirement. To achieve accurate estimates from the HECM (FHA-insured) calculator, it’s important to input some key data.
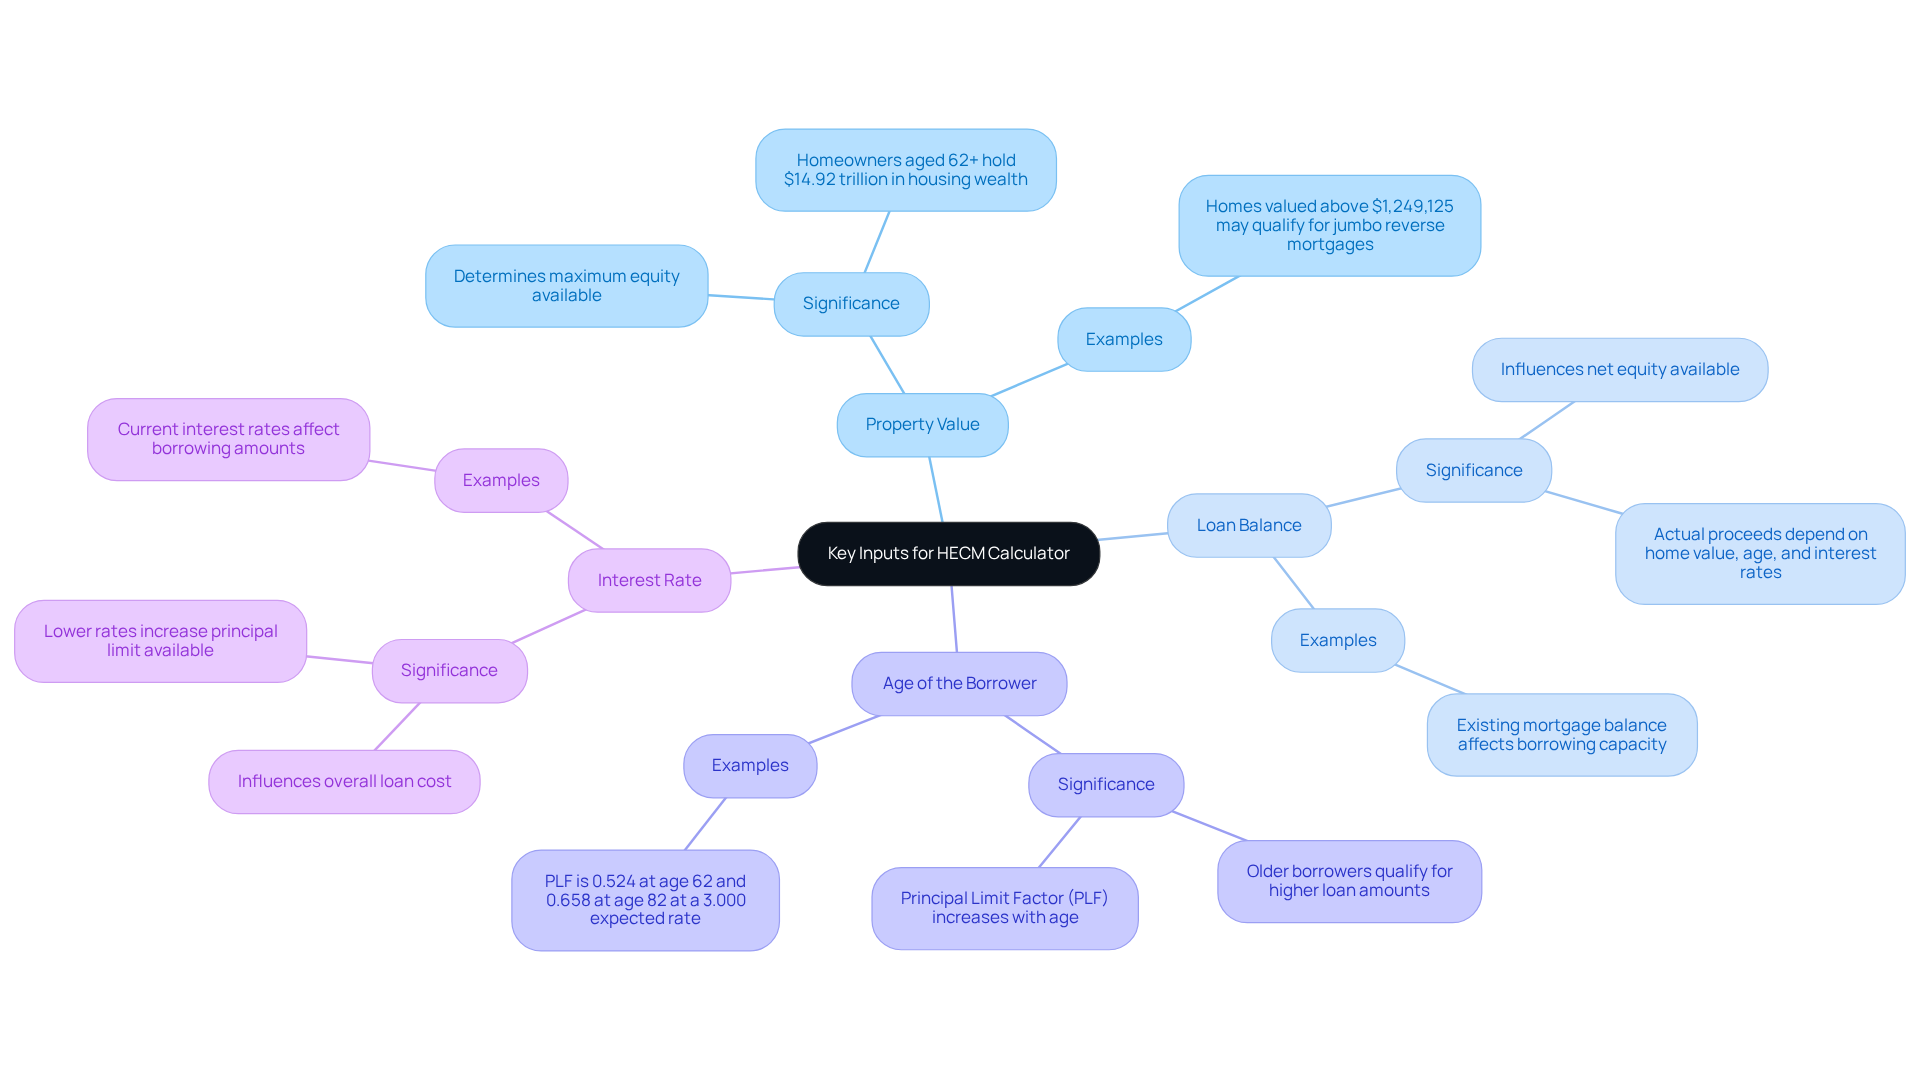
First, consider your Property Value. The current appraised worth of your home is essential, as it determines the maximum amount of equity available. Homeowners aged 62 and older hold approximately $14.92 trillion in housing wealth, making this input particularly significant.
Next, think about your Loan Balance. If you have an existing loan, the remaining amount must be entered. This figure will influence the net equity available through this financing option, as the actual proceeds rely on the home value, age, and interest rates.
The Age of the Borrower is another significant factor. The age of the youngest borrower matters because older borrowers typically qualify for higher loan amounts due to their shorter life expectancy. For instance, at a 3.000% expected rate, the Principal Limit Factor (PLF) is 0.524 at age 62 and increases to 0.658 at age 82.
Lastly, the Interest Rate plays a role. The current interest rate influences the overall cost of the loan and the amount available to borrow. Lower expected interest rates generally increase the principal limit available to borrowers.
When you enter these details, you can get a clearer picture of the financial options available to you. Remember, the maximum claim amount for 2026 is set at $1,249,125, which can really benefit those with higher-valued homes. Furthermore, many retirees in Florida view reverse mortgages as a beneficial choice for accessing their property equity, enabling them to age in place or finance extended care. Taking the time to understand these inputs can open doors to financial security and peace of mind in your golden years.
Interpret Results and Understand Their Implications
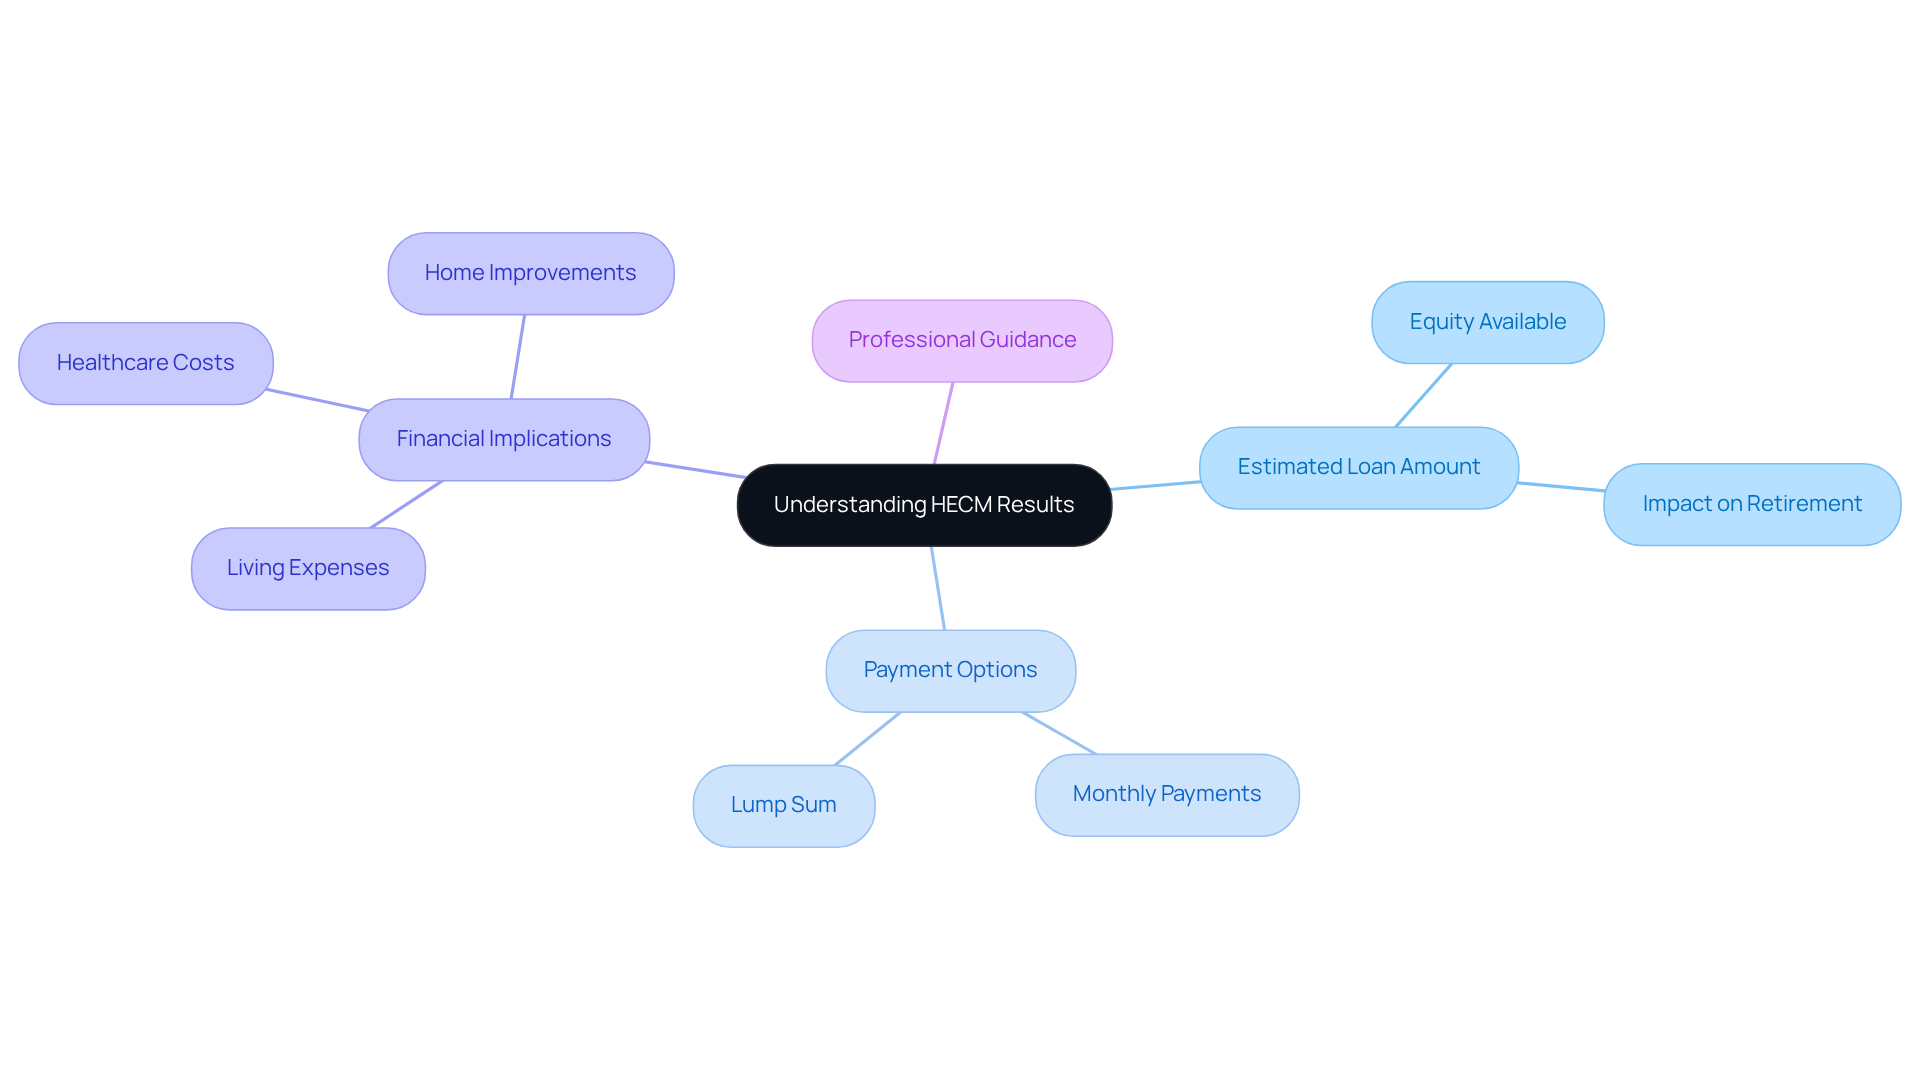
Receiving estimates from the HECM calculator can feel overwhelming, but understanding them is key to your financial peace of mind. The output typically includes the estimated loan amount, reflecting the equity available to you as a homeowner. Additionally, the calculator may outline potential monthly payments or lump sum options. It’s important to grasp these figures, as they can really shape your retirement journey.
It can be overwhelming to decide how to best use these funds for your needs – whether for covering living expenses, healthcare costs, or home improvements. Remember, these estimates are not definitive proposals; they serve as a starting point for deeper conversations with a home equity professional who can help you explore tailored options.
Many homeowners with equity are discovering how these financial products can provide much-needed support during tough times. For instance, those facing financial pressures from rising insurance premiums and healthcare costs may find these options particularly appealing. This shift means more choices for you, but it can also feel daunting to navigate these options.
As you interpret your calculator results, keep in mind that many Americans are grappling with rising living costs and inflation. It’s vital to assess how a reverse mortgage fits into your broader retirement strategy. By reaching out to a professional, you can find the support you need to navigate these choices with confidence and clarity.
Conclusion
Many retirees feel uncertain about their financial options, especially when it comes to sharing personal information. This calculator can help retirees feel more comfortable exploring their options for Home Equity Conversion Mortgages (HECMs), allowing them to assess their home equity and potential loan amounts securely. Using this resource can help you understand how to improve your financial situation during retirement.
Throughout the article, we shared key insights about the functionality of the reverse mortgage calculator, including the importance of inputting accurate data such as:
- Property value
- Loan balance
- Age of the borrower
- Current interest rates
These factors significantly influence the estimates provided, guiding retirees in understanding their financial landscape. We also discussed the implications of these estimates, emphasizing the need for further exploration with a professional to tailor options that align with your retirement goals.
Ultimately, using a reverse mortgage calculator anonymously not only protects your personal information but also opens up avenues for financial security. As you navigate the complexities of your financial future, embracing tools like this calculator can lead to more informed choices. Engaging with a certified professional can further enhance your understanding and ensure that the right decisions are made to support a fulfilling retirement. Taking that first step towards understanding your options can lead to a brighter, more secure future.
Frequently Asked Questions
What is a Home Equity Conversion Mortgage (HECM)?
A Home Equity Conversion Mortgage (HECM) is an FHA-insured loan that allows eligible homeowners to access a portion of their home equity through options such as a cash lump sum, line of credit, or monthly payments.
What is the purpose of a HECM?
The purpose of a HECM is to provide retirees with additional income during retirement, helping them manage living costs, healthcare expenses, or home renovations without the stress of monthly payments.
Who retains ownership of the property with a HECM?
The borrower retains ownership of the property, and the loan becomes due only when the last borrower permanently leaves the home, sells the property, or passes away.
Why do fewer retirees utilize reverse financing options?
Despite the benefits, fewer than 2% of retired households utilize reverse financing options, indicating that many retirees may be missing out on a valuable opportunity to improve their financial security.
How can retirees in Florida benefit from a HECM?
Many older homeowners in Florida have significant equity in their homes, and with a median property price of $415,762 in 2022, tapping into this equity through a HECM could greatly enhance their financial situation.
What are the advantages of HECMs compared to conventional loans?
Unlike conventional loans that require monthly payments, HECMs allow retirees to access their home equity without the burden of monthly payments, making it easier for them to maintain their lifestyle during retirement.
Have questions about this?
Talk to a Certified Reverse Mortgage Professional — directly.
When you call, you reach me — not a call center. Free 30-minute consult by phone, video, or in person. No SSN, no credit pull, no obligation.
Schedule a consult